The Single-Family Rental Market, and What’s to Come!
Paving the Way Forward, Part 2
In Part 1, I looked at build-to-rent and how purpose-built rental communities are helping address housing supply. Build-to-rent, though, is only one slice of a much larger asset class. In Part 2, I turn to the broader single-family rental (SFR) market: what the new ROAD to Housing legislation means for single-family investors, where SFR stands today, the outlook for 2027, and the strategies investors are using to stay ahead.
What the ROAD to Housing Act means for single-family investors
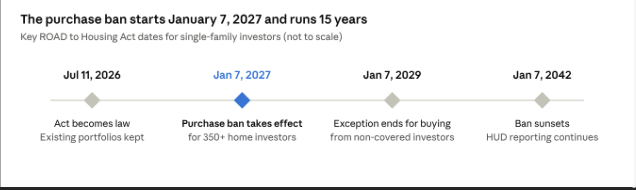
The biggest change to the SFR playbook in a decade is now law. The ROAD to Housing Act bars large institutional investors from buying existing single-family homes, starting January 7, 2027.
The key rules. The ban applies to anyone controlling 350 or more single-family homes, including affiliates acting together. No one is forced to sell homes they already own. Violations carry penalties of up to $1 million or three times the purchase price, and the ban sunsets in 2042.
The exceptions matter just as much. Large investors can still build or buy new build-to-rent homes, renovate code-deficient homes (investing at least 15% of the price), run rent-to-own programs and buy from other large investors. A separate, temporary exception lets them buy from investors not covered by the Act (those below the 350-home threshold) for two years, through January 7, 2029. It is not a deadline for smaller investors themselves, who can keep buying.
What it means for investors:
- Build-to-rent becomes the main growth path for large operators, reinforcing the case I made in Part 1.
- Smaller investors gain an edge in the resale market, with less institutional competition for existing homes.
- Existing institutional portfolios become more valuable, since they are now harder to replace.
- Treasury may issue additional guidance, but investors approaching the 350-home threshold should review their ownership structures and growth plans now.
Where SFR stands today
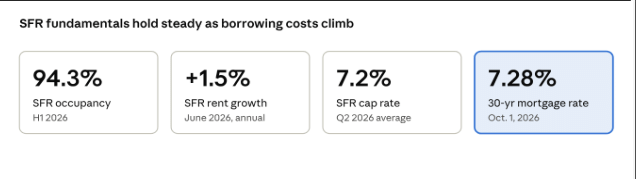
Single-family rentals remain one of the steadiest corners of real estate: occupancy is strong, rent growth is modest but improving, and the cost of owning keeps renters renting longer.
A few themes stand out:
- Renting still beats buying on monthly cost. Buying cost roughly 35% more per month than renting in early 2026. With rates close to 7% this fall, that gap keeps families in rentals longer and supports retention.
- The lock-in effect is limiting resale supply. About 70% of homeowners hold mortgages at 5% or below, so fewer existing homes come to market.
- Growth has shifted to the Midwest and Northeast. Chicago, Detroit and Philadelphia are among the markets leading rent growth, reflecting a broader shift toward the Midwest and Northeast
- The high end is outperforming. High-end single-family rents rose 2.4% year over year in June, while low-end rents rose just 0.4%, a sign of affordability strain at the bottom of the market.
- Institutions are a small slice of the market. Investors with 350+ homes own about 5% of the nation’s 14 million single-family rentals and made about 1% of 2025 home purchases, down from a 4% peak in 2022. The rest of the market belongs to small and mid-size owners.
The 2027 outlook
2027 looks like a year of higher-for-longer rates, thinner new supply and a new rule book, a mix that favors owners of well-located rental homes and challenges anyone relying on cheap debt.
- Rates stay elevated. Higher rates keep would-be buyers renting, but they also raise borrowing costs and put pressure on cap rates.
- Home price growth cools. The MBA expects national price growth of roughly 2% to slow further in 2027 before picking up in 2028. That means less appreciation upside, so returns lean more on rental income and operations.
- New construction slows. Fewer single-family and multifamily starts are expected in 2027. That pullback in new supply gives oversupplied markets time to absorb recent deliveries and get rent growth back on track.
- The shortage persists. Realtor.com estimates the U.S. is about 4 million homes short. Rental demand has a structural floor that rate cycles do not erase.
- The ROAD Act goes live. The purchase ban starts January 7, 2027. Expect Treasury’s proposed rules, the first HUD ownership reports, and repositioning by large operators toward build-to-rent, renovate-to-rent and rent-to-own programs.
My take: rent growth should stay positive and modest nationally, with leadership in supply-constrained Midwest and Northeast markets and a gradual recovery in the Sun Belt as deliveries fall. The biggest change will be in who is buying, not whether people are renting.
Strategies investors are using to stay ahead
Against this backdrop, the investors best positioned for 2027 are rethinking how they acquire properties, structure capital and manage operations.
- Leaning into build-to-rent. BTR is now the clearest legal growth path for scale operators, and it delivers new, low-maintenance homes that command premium rents. Partnerships with builders, including forward purchases of new communities and scattered new lots, are becoming a core sourcing channel.
- Adding value through renovation. The renovate-to-rent exception rewards investors who take on homes that need real work. Buying distressed or code-deficient homes and investing 15% or more of the price brings older housing stock back into service and creates value through the rehab.
- Building rent-to-own and homeownership pathways. Qualifying homeownership programs can create pathways for renters to become buyers, while offering investors a way to differentiate themselves with residents and policymakers.
- Buying where supply is tight. Midwest and Northeast metros with little new construction are leading rent growth. In the Sun Belt, patient investors are buying at today’s softer pricing ahead of the supply slowdown.
- Staying below the threshold, deliberately. Small and mid-size investors now have an edge in the resale market. Those approaching 350 homes are reviewing ownership structures, affiliate relationships and growth plans with counsel before the rules take effect.
- Underwriting for 7% money. Investors are stress-testing deals at today’s rates, using assumable or seller-financed debt where possible, keeping leverage moderate and building returns on cash flow rather than appreciation.
- Running tighter operations. With rent growth modest, net operating income comes from retention, expense control and technology: smart-home features, self-guided tours, data-driven pricing and preventive maintenance. Keeping a good resident is the cheapest way to grow NOI.
- Watching the portfolio trade market. Purchases between large investors remain permitted, and large investors can buy from sellers not covered by the Act until January 7, 2029. Portfolios that come to market in this window may be among the best opportunities of the cycle.
Paving the way forward with SFR
The ROAD to Housing Act does not end single-family rental investing. It redirects it.
Large capital is being steered toward building, renovating and creating paths to ownership, while the existing-home market opens up for smaller investors. Add higher rates, slowing construction and a persistent housing shortage, and 2027 rewards investors who are disciplined, local and focused on adding supply.
Together with Part 1, the message is the same: the future of single-family rental belongs to investors who add to the housing supply, not just trade it.
I’d love to hear how you’re adjusting your strategy for 2027. Connect with Auben, or find me at the next IMN event!
Kristen Brady, Auben
Sources:
This article is for informational purposes and is not legal or financial advice. Investors should review the Act’s requirements with their own counsel.