Skip to content

Rental Renovation ROI: How to Calculate It and Spend Wisely

Rental renovation ROI is the annual rent your upgrade adds, divided by everything the project costs you, including lost rent while the unit sits empty. A $10,000 upgrade that adds $100 a month returns 12% a year before financing, taxes and vacancy. The number only holds if the rent premium is real for your submarket, so the work is in testing that premium before you spend. Owners who want the calculation, the contractors and the rent comparison handled by one team can bring the project to Auben’s project management service.

Aubenrealty
Consider Renovation Support for Rental Properties
Explore Auben Realty’s real estate investment and property management approach, including renovation services for property owners and investors.

TL;DR

  • Simple ROI is (annual rent increase ÷ total renovation cost) × 100. Count lost rent, carrying costs and a contingency in the cost, not just the contractor’s bid.
  • Work backward: divide the cost by 12 and by your target yield to get the monthly rent premium you need, then check it against comparable rents nearby.
  • Match the scope to the submarket’s rent ceiling. Finishes that outrun the neighborhood do not earn their cost back.
  • Capital improvements to a residential rental are depreciated over 27.5 years, and permits may be required. Confirm both with a tax advisor and your local building department before work starts.
  • Renovate between tenants and sequence multi-unit work as units turn over, so you never pay for avoidable vacancy.

Table of Contents

The basic ROI formula for a rental renovation

The most common version is simple: annual rent increase divided by renovation cost, times 100. One investor guide states it exactly that way. Another landlord resource gives a worked case: a $10,000 upgrade that adds $1,200 a year in rent yields a 12% return.

A quick screen many landlords use is the 1% rule for upgrades: the monthly rent increase should be at least 1% of the cost, so a $10,000 project should add $100 a month. HonestCasa pairs it with a payback test, calling under 24 months a strong investment and under 12 months excellent. Treat these as screens, not guarantees. They tell you whether a project deserves a closer look.

Payback period: the second number to know

ROI tells you the yearly yield. Payback tells you how long your cash is tied up. Divide the total cost by the added monthly income to get months to recover the spend. One interior renovation analysis shows how much the market matters: a $4,000 per-unit scope that earns an $80 monthly premium pays back in about 4.2 years, while the same scope in an over-improved submarket earning only $40 a month takes about 8.3 years.
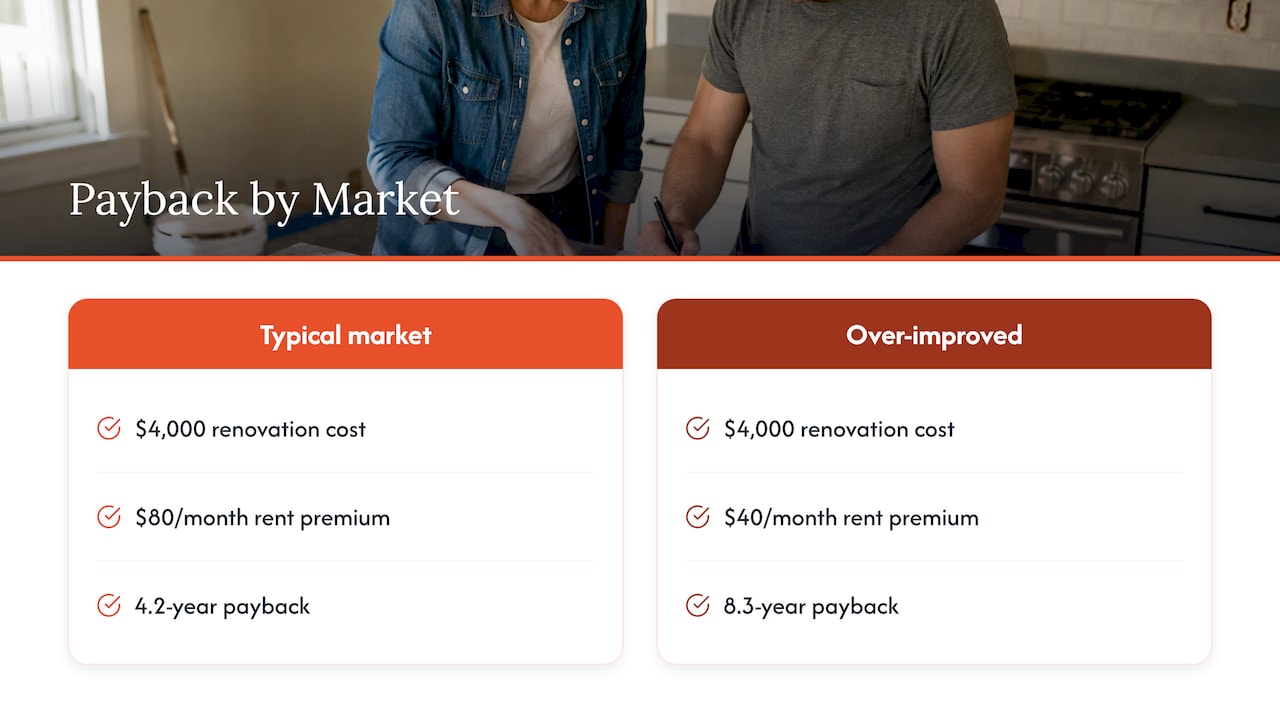
Payback time compared across two rental scenarios

The same work, the same cost, and a payback that doubles. That is why comparing the payback to your planned holding period matters more than any rule of thumb.

What belongs in the cost side

Most ROI mistakes happen in the denominator. A contractor’s quote is only part of what the project costs you.

Costs that are easy to forget

  • Lost rent while the unit is down. One payback calculator adds the prior monthly rent multiplied by the months with no rent to the renovation cost, which is the honest way to count it.
  • Carrying costs. Experienced investors count construction, permits, financing, insurance, property taxes and utilities. A hard-money lender’s guide points out that a six-month renovation that stretches to nine months adds three more months of interest, taxes, insurance and utilities.
  • Permits and contingency. One per-unit budgeting guide shows a $14,000 hard-cost renovation becoming $17,000 to $19,000 once you add 15% contingency, $1,500 in carry cost and $800 in permits.
  • Management fees for running the project. If someone else coordinates bids, schedules and inspections, that fee is part of the project cost, and so is your own time if you do it yourself.
  • Financing. Borrowing changes the math. A 12% cash return on a renovation can shrink once interest is deducted, so run the calculation both with and without the loan.

Worked example

Say you plan a $9,000 refresh of a three-bedroom single-family rental: paint, flooring, a new vanity and lighting.

Line item Amount
Contractor bid $9,000
15% contingency $1,350
Lost rent (3 weeks at $1,800/month) about $1,250
Permits and carry $600
Total cost about $12,200

If the work lifts rent from $1,800 to $1,950, the added income is $150 a month, or $1,800 a year. Simple ROI is $1,800 ÷ $12,200, about 14.8%. Payback is roughly 81 months of the premium alone. The example is illustrative, not a market figure. The point is that the bid alone ($9,000) would have suggested a 20% return, and the full cost cuts it by a third.

What counts on the benefit side

Rent increase is the headline, but three benefits can feed the return:

  1. Higher rent. The premium over comparable unrenovated units.
  2. Lower vacancy. Cosmetic work often earns its keep by getting units rented faster rather than by lifting rent. Our guide to reducing your rental vacancy rate covers the days-on-market side. Count the saved vacancy days in dollars: at $1,800 a month, each week saved is worth roughly $420.
  3. Lower operating cost and higher value. New systems can reduce repair calls. Added net income also raises what the property is worth: divide the annual net income increase by the local cap rate. That calculator-style estimate only holds if buyers price the property on income, and it ignores financing, taxes and the time value of money.

Institutional operators set the bar higher than most small landlords. One value-add guide for asset managers says they commonly target a 15% to 25% unlevered return on renovation cost, with payback under 36 months. Another investor guide cites a common goal of $2 back in value or rent for every $1 spent over the hold period.

How to estimate whether an upgrade will actually raise rent

This is the question that decides the whole calculation, and it is answered by comparison, not by theory.

  1. Pull comparable listings. Find at least five active and recently leased rentals within a mile or so, same bedroom count and similar age. Separate renovated from unrenovated and note the gap in rent.
  2. Identify what the premium units have. If every renovated comp has quartz counters and luxury vinyl plank, those are the features tenants are paying for. If they only have fresh paint, a full kitchen gut will not be paid for.
  3. Check days on market. A renovated unit priced at the top of the range but sitting for six weeks has not earned its premium.
  4. Apply a haircut. Use the low end of the premium range in your base case, not the average.
  5. Ask which kind of return you are buying. Kitchen and bathroom work tends to move rent most, and paint and flooring tend to shorten vacancy rather than raise rent, according to a 2026 landlord publication reporting on the UK market. US results depend on the submarket, so verify with local comps. If you are weighing bathroom updates, this guide to bathroom renovation ideas can help you compare scopes and budgets before you collect bids.

Our own write-up on the best renovations for your rental property goes through which upgrades tenants respond to, and the guide on making a single-family home more appealing to renters covers the smaller touches.

Avoiding over-renovation

Over-renovating is the most common way a rental project loses money. The rent ceiling in your submarket limits what any scope can earn.

The backward formula

Instead of asking what a renovation will earn, ask what it must earn. One budgeting guide uses: required monthly rent premium = (renovation cost × target yield) ÷ 12. For a $15,000 per-unit budget at a 10% target yield, that is $125 a month. If comparable rents do not show a $125 gap, the scope is too big.

The hold-period test

Take the target post-renovation rent, subtract the current rent, and divide by 12 if you are working from annual figures, or use the monthly gap directly. Then compute payback. If payback runs longer than you plan to own the property, the project is over-scoped for your business plan.

Match the neighborhood

The best-returning scope is the one calibrated to the submarket’s rent ceiling and your property’s position within it. The same analysis notes that a Class C submarket where Class B rents are $1,200 a month cannot support the renovation spend of a Class B submarket where Class A rents are $1,800. Another guide puts it plainly: luxury finishes in a Class C neighborhood do not command a premium.

Stress-test the deal

Professional investors pressure-test deals: if costs rise, does the project still work? If the property sells for less than expected, is the margin still acceptable? Rerun your numbers with costs 15% higher and the rent premium 25% lower. If the return survives, the plan is sound.

Timing, sequencing and multi-unit work

Vacancy is the hidden cost of renovation, so schedule work to coincide with natural turnover. For multifamily, renovate as units turn over rather than emptying a building at once. For a single-family home, line the work up between tenants and aim to finish just ahead of the strongest leasing months. Our notes on leasing season explain why timing the listing matters as much as the work itself.

Curb appeal is a low-cost lever that sits outside the interior budget. See our curb appeal tips for what tends to matter at showing time.

Tax and permit rules to check first

These are the two items that can change your return after the check is written.

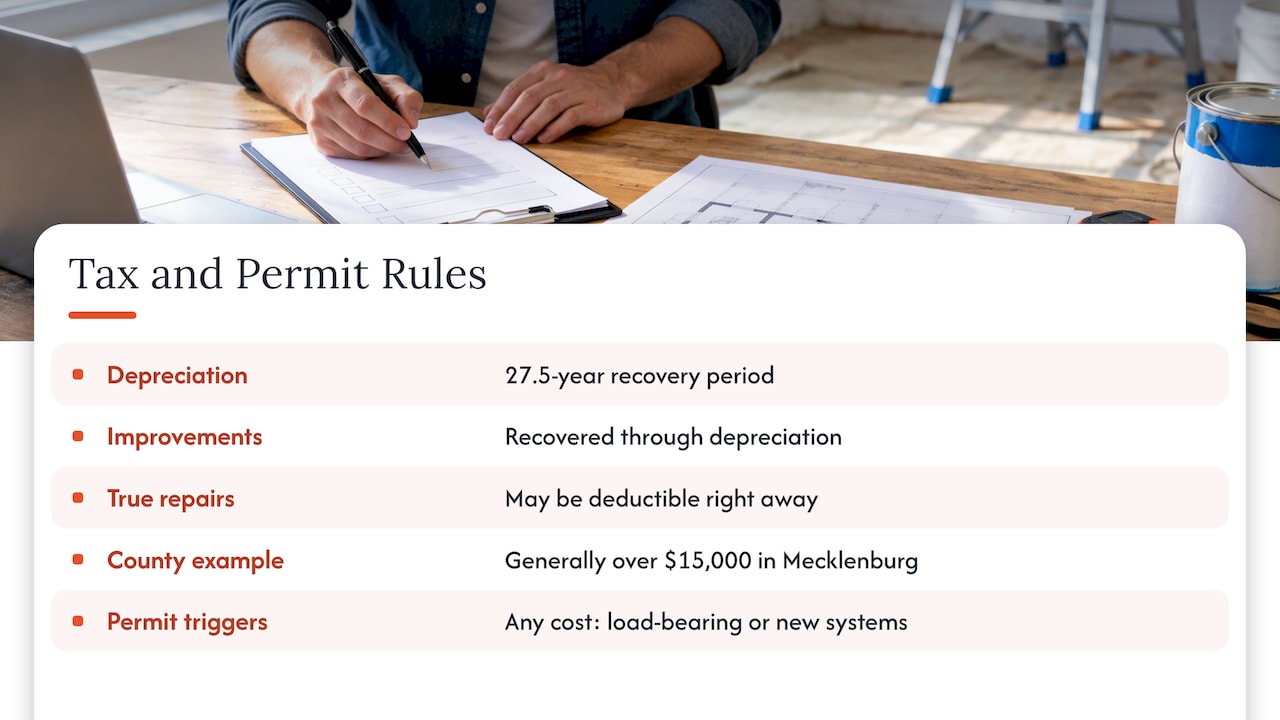
Depreciation. For residential rental property, the IRS sets a recovery period of 27.5 years under the general depreciation system. The same IRS publication says the cost of improvements is recovered through depreciation. In practice, a capital improvement is typically spread over decades instead of deducted in one year, while a true repair may be deductible right away. The line between repair and improvement is a judgment call, and bonus depreciation rules change, so talk to your CPA or tax advisor before a large project.
Tax and permit rules to check first

Permits. Rules are local. As one example, in Mecklenburg County, NC, permits are generally required for work costing more than $15,000, and regardless of cost for work involving load-bearing structures or new plumbing, heating, air conditioning or electrical systems. Check your own city or county building department before you sign a contract, because unpermitted work can create problems at resale and with insurance.

Where owners lose money on renovations

  • Budgeting the bid, not the project: no contingency, no carry, no lost rent.
  • Copying a neighbor’s finishes without checking what the neighbor’s tenants pay.
  • Choosing scope by taste instead of by the rent gap in comps.
  • Letting a project drift from six months to nine while interest and taxes keep running.
  • Skipping the tax conversation until after the work is done.

Perspective

Most renovation disappointments we see start before the first contractor shows up: the scope was set by what looked good, not by what the submarket would pay. After more than 15 years and 2,700 properties served across 10 regional markets, our view is that the return is decided on paper first.

That is why we pair local market knowledge with an investor’s discipline. We ask what rent the neighborhood supports, work backward to the budget that earns it, and hold the scope to that number. A pod-based team means the people who know your property and your market stay close to the project, and our in-house maintenance and transparent vendor selection are built to keep costs visible and the schedule honest.

Renovation is also a leasing decision. We think about resident retention and days on market from day one, because a unit that rents quickly and stays rented is where the real yield comes from. Our goal for owners is a property that performs, with as little of their own time spent as possible.

MediaBeast

Let us run the numbers and the project

If you would rather not coordinate bids, schedules and inspections yourself, our project management service covers renovation oversight, and our property management team handles leasing and day-to-day operations once the work is done. Investors looking at the portfolio level can look at asset management. We serve Charleston and Columbia, SC, Dallas-Fort Worth and Houston, TX, Kansas City and Overland Park, and Jacksonville and Jacksonville Beach, FL, among our markets.
Aubenrealty

For a deeper walk-through of planning, see our practical owner’s guide to rental renovation management.

FAQ

What is a good ROI on a rental renovation?

It depends on your hold period and financing. A common small-landlord screen is a monthly rent increase of at least 1% of the project cost, which equals a 12% annual return. Larger operators often aim higher, with 15% to 25% unlevered returns and payback under 36 months.

Should I count lost rent in the calculation?

Yes. Add the rent you give up while the unit is empty to the renovation cost. Add carrying costs such as taxes, insurance and utilities too, since they continue during the work and rise if the schedule slips.

How much contingency should I budget?

A 15% contingency is a common planning figure in per-unit renovation budgets. Older homes with unknown conditions behind walls may warrant more, so ask your contractor what has not been inspected.

Are renovation costs tax deductible for a rental?

Capital improvements are generally recovered through depreciation, 27.5 years for residential rental property, while repairs may be deductible in the year they are paid. The classification depends on the work, so confirm with a CPA or tax advisor before a large project.

Sources

Where to Invest in Kansas City Real Estate in 2026

The best places to invest in Kansas City right now depend on what you want from the property. Northern submarkets and Independence lead on rent growth and cap rates. Waldo and Volker offer deep renter pools near UMKC and the streetcar. Overland Park and Leawood are steadier, lower-yield stability plays. This guide compares them with the numbers, then shows how to match an area to your budget and risk tolerance.

We manage and sell rental property across 10 regional markets, Kansas City and Houston among them. Investors often ask us to set the two side by side, so we point to that comparison where it helps.

Aubenrealty
Invest with Less Hands-On Work
Auben Realty combines local market expertise with property management, renovation, and tenant placement across Kansas City and other regional markets.

Visit

TL;DR

  • Northern submarkets (Platte, North Kansas City, Gladstone/Liberty) and Independence are where recent rent growth and higher cap rates show up.
  • Waldo and Volker suit investors who want renter demand tied to UMKC, young professionals and the streetcar corridor.
  • Overland Park and Leawood are stability plays: higher entry prices, thinner yields.
  • At today’s mortgage rates, rent covers a loan at 1.25 debt coverage in only a narrow slice of ZIP codes, so underwrite every deal line by line.
  • Kansas and Missouri differ on taxes, eviction timelines and rent control, so pick the side before you pick the street.

Table of Contents

What the Kansas City market looks like right now

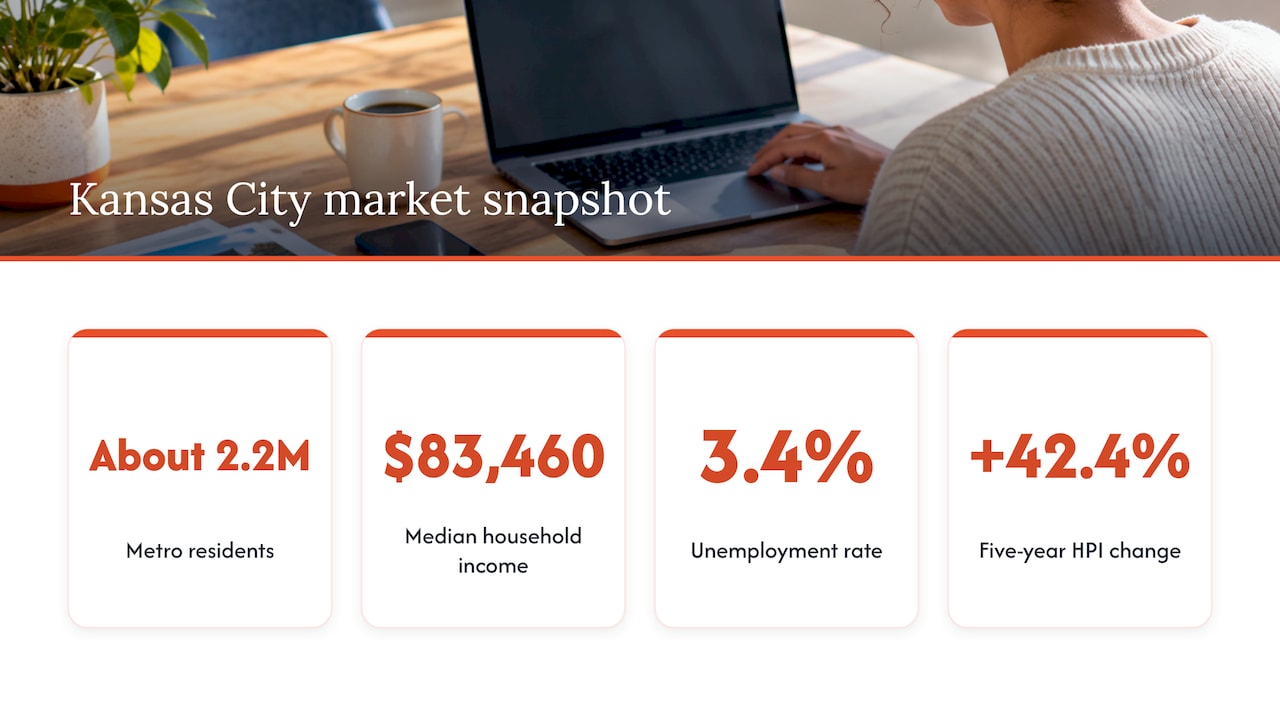
The metro holds about 2.2 million residents, with a median household income of $83,460 and unemployment of 3.4%, close to the national figure, according to REI Prime’s 2026 market data. The same source puts the price-to-income ratio at 3.4, a little under the national median, and shows the House Price Index up 42.4% over five years.

Prices have kept rising, but not fast. Saving KC Research reported in October 2026 a metro median home price of $315,000, up 4.7% from a year earlier, with 19.0% of MLS sales paid in cash. Homes took a median 35 days to sell, up from 32, and pending sales fell 15.8%.

On the multifamily side, the picture is mixed. Northmarq’s Q2 2026 report shows vacancy trending higher as completions accelerate, with net absorption under 100 units in the first half of 2026 against more than 1,300 in the same period of 2025. Vacancy is estimated to reach 8% by the end of 2026. Absorption should stay positive, though, which leaves operators room to keep raising rents where new construction has been light.

Capital is still moving in. Institutional Property Advisors reports that the average price per unit climbed 4% year over year as of March 2026, with deals from $1 million to $10 million up 35% and deals above $20 million up 65%.

What the Kansas City market looks like right now

The northern submarkets: where rents are growing

If your priority is rent growth, look north of the river. Northmarq found the northern submarkets were the metro’s top performers in Q2 2026. Platte led, with vacancy down 150 basis points. North Kansas City, Gladstone/Liberty and Independence were the top areas for rent growth, with asking rents up an average of 3.1% year over year.

The pipeline explains part of this. IPA’s report says development is shifting to the Missouri side, with Central Kansas City anchoring 23% of deliveries and Lee’s Summit-Blue Springs-Raytown about 20%. Submarkets that get fewer new units face less new supply competing for tenants.

Independence and North Kansas City

These are the cash-flow markets. Crown Mortgage’s September 2026 guide cites Independence median prices of $170,000 to $220,000 against rents of $1,100 to $1,400, producing cap rates around 6.5 to 7%, and some stabilized properties reaching 7 to 8%. North Kansas City cap rates are commonly cited between 7 and 9%.

What to check: these are older housing stocks. Budget for roofs, sewer laterals and HVAC, and price renovation before you offer. Cap rates quoted in guides are starting points, not your numbers.

Waldo and Volker: renter demand near the core

Waldo

Waldo sits in the heart of Kansas City, Missouri, with an active business association, the Waldo Area Business Association, founded in 1965. Its Community Improvement District, established in 2009, funds daily trash removal, graffiti removal, landscape maintenance and daily security patrols. That kind of upkeep helps hold tenant interest on the commercial streets near your rental.

On price, sources differ with the property type and date. DSCR Direct’s March 2026 guide lists Waldo single-family homes at $220,000 to $400,000 with rents of $1,400 to $2,200. Crown Mortgage describes entry costs generally from $350,000 with cap rates of 4 to 5%, backed by a deep pool of UMKC students and young professionals. Treat Waldo as a balanced play: appreciation and tenant depth over top yield.

Volker

Volker runs from 31st Street to 43rd Street, with State Line Road on the west, per Flatland KC. Lendmire’s July 2026 guide reports duplex rents of $2,450 a month near UMKC, a location directly on the extended KC Streetcar line, and more than 150 properties bought by local investors along the corridor before the line opened.

If you plan to rent short term in Volker, read the rules first. The neighborhood association president told Flatland KC that unlicensed short-term rentals have multiplied and that enforcement is a concern. Licensing and compliance should be part of your plan, and a long-term lease to a UMKC-area tenant sidesteps the question.

Crossroads and the urban core

The Crossroads Arts District sits just south of downtown Kansas City, Missouri, north of Union Station, east of I-35 and west of Troost. It is a strong lifestyle address. For investors, the numbers deserve care: Lendmire cites the Crossroads, Midtown and Crown Center corridor running vacancy above 13%, even as citywide occupancy is projected near 93.4% by year-end.

In practice, urban-core units compete with new apartment deliveries. Parking can also affect rentability: the district lists public garage parking at $55 a month and public lot parking at $40 a month. Include parking in your tenant offer.

Overland Park, Leawood and Parkville: the stability plays

Northmarq expects Overland Park to remain the leading area for multifamily sales activity, though its share may thin as deals close elsewhere. The city’s official recreation page lists a 300-acre arboretum, a 96-acre soccer complex with 12 lighted turf fields and the Deanna Rose Children’s Farmstead. Those amenities help keep family tenants in place.

Leawood is the high-price end of the Kansas side. Lendmire puts the median sale price near $761,000 and describes it as a stability play rather than a yield play, with cap rates of 4 to 6%. Repit’s 2026 data for ZIP 66206 shows an average home value of $769,928 against rent of $2,285, a 2.3% cap rate, and a 5-year CAGR of 7.5%. Buy here for preservation and long-tenure tenants, not monthly cash flow.

Parkville is more moderate. Prop:Metrics data as of May 2026 shows a median price of $354,000 (up 1.9%), median rent of $1,820 (up 5.0%) and 45 median days on market. Price figures vary by source and ZIP definition, so compare like with like.

Neighborhood comparison

Area Typical entry price Typical rent Cap rate signal Best for
Independence, MO $170,000 to $220,000 $1,100 to $1,400 6.5 to 7%, some 7 to 8% Cash flow
North Kansas City, MO Varies by property Rents up 3.1% in the northern submarkets 7 to 9% commonly cited Yield with rent growth
Waldo, MO $220,000 to $400,000 $1,400 to $2,200 4 to 5% (entry $350,000+) Balanced, deep tenant pool
Volker, MO Varies by property Duplex $2,450 Not stated Streetcar and UMKC demand
Parkville, MO $354,000 median $1,820 median Not stated Moderate-price suburban
Leawood, KS About $770,000 $2,285 2.3% in ZIP 66206 Stability

Missouri or Kansas: rules that change the math

The state line changes your costs. First Home Start Guide’s February 2026 analysis notes the Kansas side has no state transfer tax and no mortgage registration tax, a 3-day nonpayment eviction notice versus Missouri’s 5-day, and a statewide rent control ban under K.S.A. 12-16,120. The Missouri side offers lower median home values in Kansas City proper and no Wyandotte County mill levy cutting into net operating income.

Rules change, so confirm current law and local ordinances with a licensed Missouri or Kansas attorney before you sign a lease template or serve a notice.

One more development: the Kansas City Business Journal reported on November 9, 2026 that the federal government designated Opportunity Zones across the KC area, from downtown to Olathe, on both sides of the state line. If a property sits in one, ask your tax adviser how the incentive applies to your situation.

The financing reality check

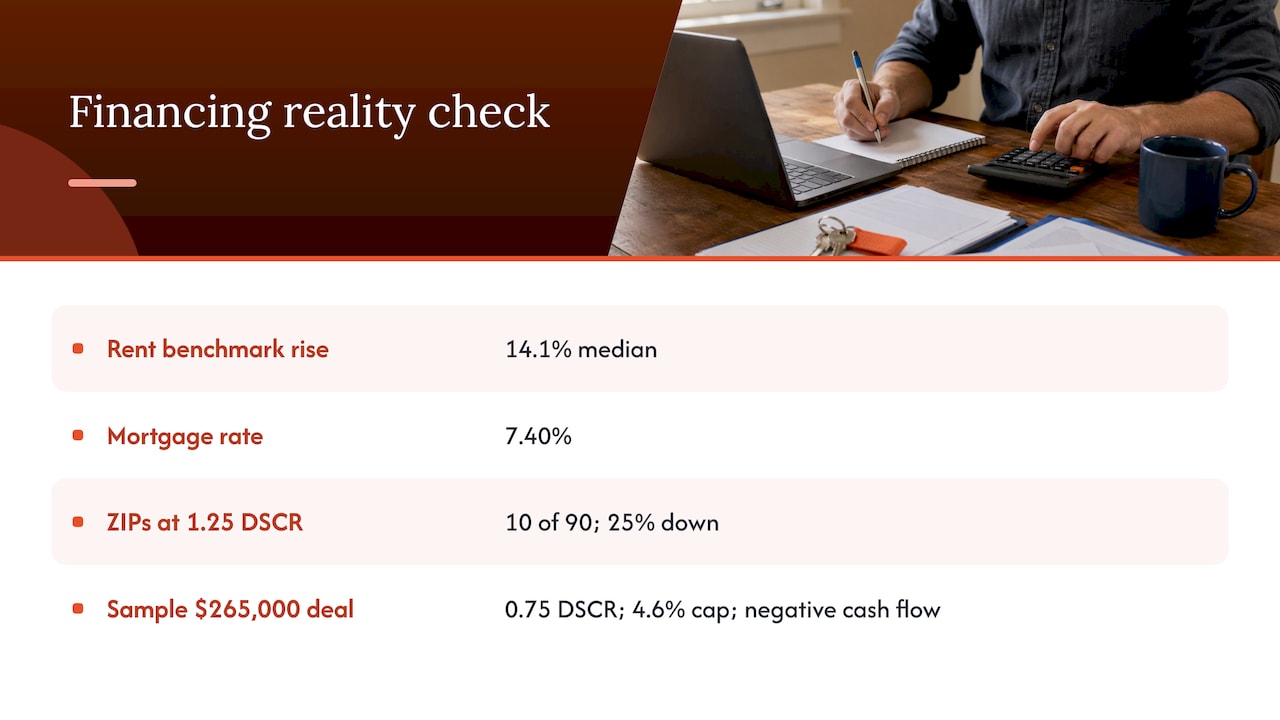
Higher rents do not automatically mean easy deals. Saving KC Research found that after HUD’s Kansas City rent benchmarks rose a median 14.1% on October 1, 2026, at a 7.40% mortgage rate rent covered a 25%-down loan at 1.25 debt coverage in only 10 of 90 ZIP codes with enough sales.

Price bands matter too. Of 4,385 closed sales in August and September, only 260 sold under $150,000, and 53.1% of those were paid in cash. In the $150,000 to $250,000 band, there were 762 sales with a 19.0% cash share. Sub-$150,000 homes draw cash buyers, so a financed offer faces more competition there.

TrueCap’s FY2026 data shows how thin a financed deal can run: a sample $265,000 purchase using a 3-bedroom HUD Fair Market Rent of $1,769 as a placeholder came to negative cash flow, a 4.6% cap rate and a 0.75 DSCR. Underwrite with real rent comps, real repair costs and a management fee.

Kansas City rental financing and coverage figures

How to match an area to your budget and goals

Start with the number you need the property to do, then work backward.

  1. Under about $250,000, cash flow first. Independence and North Kansas City are the obvious places to look. Plan a renovation budget and a reserve.
  2. $250,000 to $400,000, balanced return. Waldo, Parkville and parts of Volker give you tenant depth and appreciation potential. Expect cap rates in the middle range.
  3. $400,000 and up, preservation. Overland Park and Leawood suit investors who value stable, long-tenure tenants and can accept a thinner yield.
  4. Larger capital, multifamily or build-to-rent. Look at where the pipeline is thin, since less new supply supports rent growth, and at submarkets where vacancy is already falling.

Then check three risks for any area: new supply nearby, the true cost of repairs, and how you will handle leasing and maintenance if you live elsewhere. Our single-family rental guide walks through the single-family case.

Looking at Houston as well?

Many Kansas City investors weigh a second market. How investors compare rental markets across regions tends to come down to the same few measures: vacancy, rent growth and price-to-rent. How investors compare rental markets shows that approach in another region. For Houston, we have written about why Houston keeps attracting long-term investors and what makes Houston a top rental market.

Our perspective

Kansas City rewards investors who match the neighborhood to the plan and then run the property well. We have served 2,700 properties across 10 regional markets in over 15 years, and the pattern is consistent: returns are decided as much by operations as by the purchase price.

That is why our approach pairs local market expertise with investor-focused strategy. Our pod-based teams give each owner a focused point of contact. Our in-house maintenance and transparent vendor selection are designed to keep repair costs and turnaround under control. Proactive resident retention is meant to keep units occupied.

For an investor who does not live in Kansas City, we think the right setup is a partner who can handle acquisition, leasing, renovation oversight and asset management in one place, so you keep the returns and give up the day-to-day.

MediaBeast

How Auben can help

Whether you are buying your first rental or growing a portfolio, we cover the full path. Our brokerage services help you find and buy, property management covers leasing, maintenance and resident care, and asset management keeps a portfolio working toward your goals. For larger holdings, see our multifamily and build-to-rent services.

Aubenrealty

Talk to our team through aubenrealty.com about the Kansas City area that fits your budget.

FAQ

Is Kansas City a good place to invest in real estate?

It can be, depending on strategy. REI Prime shows prices a little below national norms relative to income, and Northmarq reports rent growth in the northern submarkets. Rising vacancy from new completions and tight financing math mean each deal needs careful underwriting.

Which Kansas City suburbs are best for rental property?

For cash flow, look at Independence and North Kansas City. For a balance of tenant depth and appreciation, Waldo and Parkville are common picks. Overland Park and Leawood suit stability-minded investors who accept lower yields.

Is Kansas City growing or declining?

The metro is growing. REI Prime reports net migration of 2,315 households and building permits for 12,321 units over the trailing twelve months, up 29.7%.

Should I invest on the Missouri or Kansas side?

It depends on costs and rules. Kansas has no state transfer tax and a 3-day nonpayment eviction notice, while Missouri’s Kansas City proper has lower median home values. Confirm current law with a local attorney.

Sources

Remote Landlord Management: How to Run a Rental From Afar

Remote landlord management means overseeing a rental you can’t reach in person. You keep the work that happens on a screen: marketing, screening, leasing, rent collection and bookkeeping. You hand the work that happens at the property, such as unit access, repairs and inspections, to a local team or to vetted vendors. Owners who do this well set up systems before the first problem arrives, and they don’t rely on a plane ticket when something breaks.

This guide covers what you can run yourself, what needs a local presence, how to build that support, and where owners most often get into trouble: screening, fair housing, emergencies and taxes.

Aubenrealty
aubenrealty.com
Manage Rentals Without Being There
Auben Realty provides property management, renovation, and tenant placement services for owners seeking less hands-on involvement.

Visit

TL;DR

  • Administrative work (listing, screening, lease signing, rent collection, record keeping) can be done remotely. Physical work (repairs, inspections, access) needs someone local.
  • Build the local layer first: primary and backup vendors for key trades, a written emergency plan and a named person who can walk the unit.
  • Use one documented process for maintenance requests, with photos or video, so problems are triaged fast and nothing lives in text threads.
  • Federal fair housing rules apply to you wherever you live, including when software screens applicants for you.
  • If the workload or distance outgrows you, a full-service property manager takes over the on-site layer and keeps you in control of the numbers.

Table of Contents

What you can run from a laptop and what you can’t

The cleanest way to think about remote ownership is a split. One side is digital and can be done from anywhere. The other side is physical and needs a person within reach of the door. A landlord guide from Shuk Rentals describes the same division: keep the laptop tasks, delegate the on-site ones.

Task Can you do it remotely? What you need
Marketing and listing Yes Good photos taken by someone local, a clear listing, a way to field inquiries
Tenant screening Yes, with care A written screening policy applied to every applicant
Lease signing and storage Yes Digital signing and a central records folder
Rent collection Yes Online payments into a dedicated account
Bookkeeping and tax records Yes Monthly categorizing and saved receipts
Routine repairs No, but you can coordinate Vetted local vendors
Emergencies No, but you can plan After-hours contacts and spending limits
Move-in and move-out inspections No A local person with a checklist and a camera

The left column is where most owners do fine. The trouble usually starts in the physical rows, because a burst pipe at 11 p.m. doesn’t care that you’re two time zones away.

Build your local layer before you need it

Every remote setup rests on the people near the property. You need at least three kinds of contact:

  1. A local point person. Someone who can open the unit, meet a vendor, take dated photos and tell you what is really happening. This can be a trusted contact, a local professional or a property manager.
  2. Primary and backup vendors for the trades that cause the most urgent calls: plumbing, electrical, HVAC and general repair.
  3. An after-hours option. Someone must answer when a tenant reports a leak at night.

How to find vendors you can trust

Start with referrals. Local landlords, investor meetups, real estate professionals and your current vendors know who shows up and who doesn’t. Then vet each candidate before assigning any work:

  • Confirm a current license and proof of insurance.
  • Ask for at least three references and actually call them.
  • Judge how clearly they communicate and how transparent their pricing is.
  • Get several quotes for non-emergency work.

Contractors also pick their favorite customers. They tend to prioritize owners who pay promptly, send photos and details up front, and don’t haggle over every service call. Being that kind of client is the cheapest way to get a fast response when you’re far away.

Owners who want a structured way to track maintenance and contractors can use a tool built for that job. This landlord maintenance guide covers the legal and cost side of repairs, and it pairs well with the written processes below.

Advertising, screening and signing a lease remotely

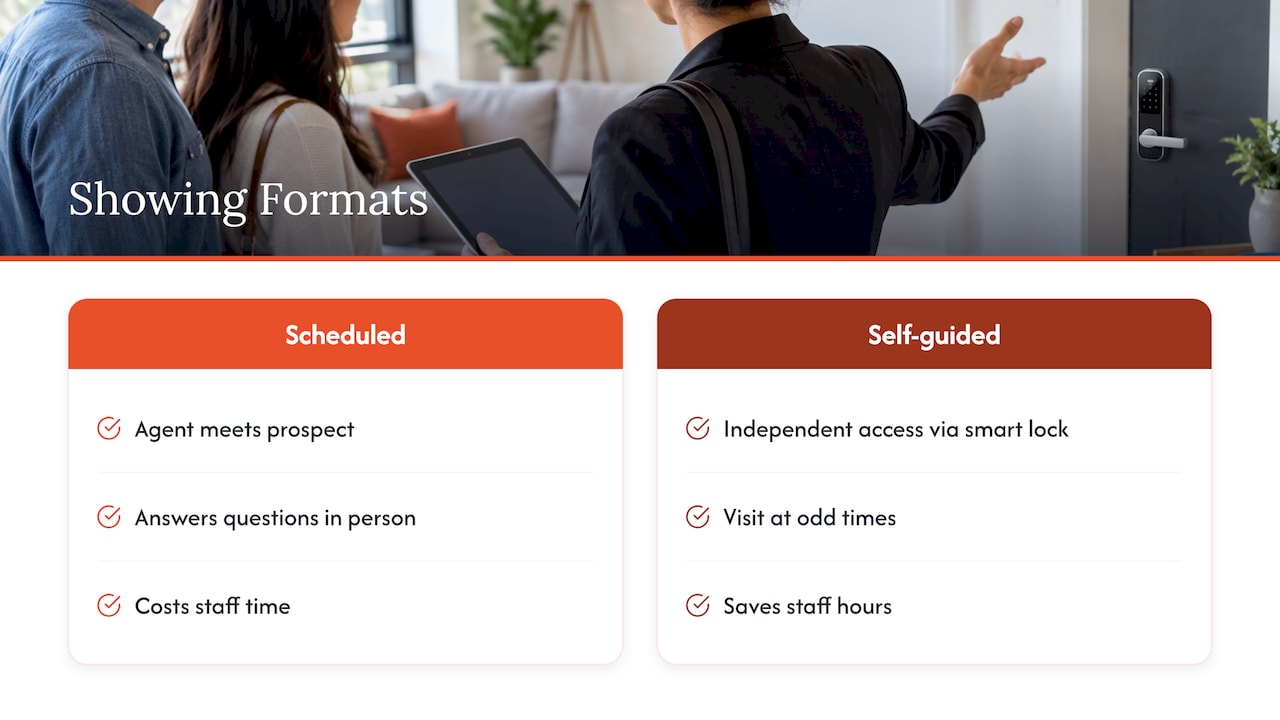
Listing and leasing are the easiest tasks to move online. Photos, a floor plan and a clear description can bring in applicants without you ever visiting. Showings are the exception: someone local usually needs to be there, or you can offer a self-guided or video tour arranged through your point person.

Screen every applicant the same way

Set your criteria in writing before you list. That means minimum income, rental history requirements, what in a credit or background report is disqualifying, and how you treat each case. Apply them to everyone.

This matters legally. According to HUD’s 2024 guidance on the Fair Housing Act and tenant screening, housing providers remain responsible for discriminatory decisions even when an automated screening service produced the result. HUD also says providers should independently check whether information in a report is truly disqualifying under their own clear, public and consistent policies. The same guidance restates that the Fair Housing Act bars discrimination based on race, familial status and other protected classes, including discriminatory statements and biased screening criteria.

In practice, a remote owner should:

  • Publish the criteria with the listing.
  • Avoid ad language that signals a preference for or against any protected group.
  • Review the underlying report, not just a pass or fail score.
  • Keep a record of why each applicant was accepted or declined.

We walk through the whole sequence in our six-step tenant screening process, and our overview of fair housing for landlords explains what the law requires. If you’d rather not run screening yourself, here is how a property management company handles tenant screening.

Sign and store the lease digitally

Digital lease signing removes the need to meet in person. Keep the signed lease, move-in condition report, addenda and tenant contact details in one organized folder that you and your local contact can both reach. When a dispute comes up a year later, that folder is your evidence.

Collecting rent and keeping clean books from a distance

Rent collection is where remote ownership can be better than local ownership, because a good online system doesn’t depend on anyone’s presence. The practices that hold up:

  • Collect through an online system, ideally ACH, that timestamps payments and can automate late fees.
  • Use a dedicated bank account for the property so rental income and expenses never mix with personal money.
  • Avoid cash and peer-to-peer apps for rent. They leave a thin paper trail.
  • Save every receipt digitally and categorize expenses monthly.
  • Reconcile monthly. Compare your records to the bank statement before small errors compound.

We lay out our own approach in the rent collection process we’ve shaped across 2,700 properties, and explain why a property manager should accept online rent payments.

Handling maintenance, emergencies and inspections

Maintenance is where distance hurts most, and where a written process helps most.

One front door for repair requests

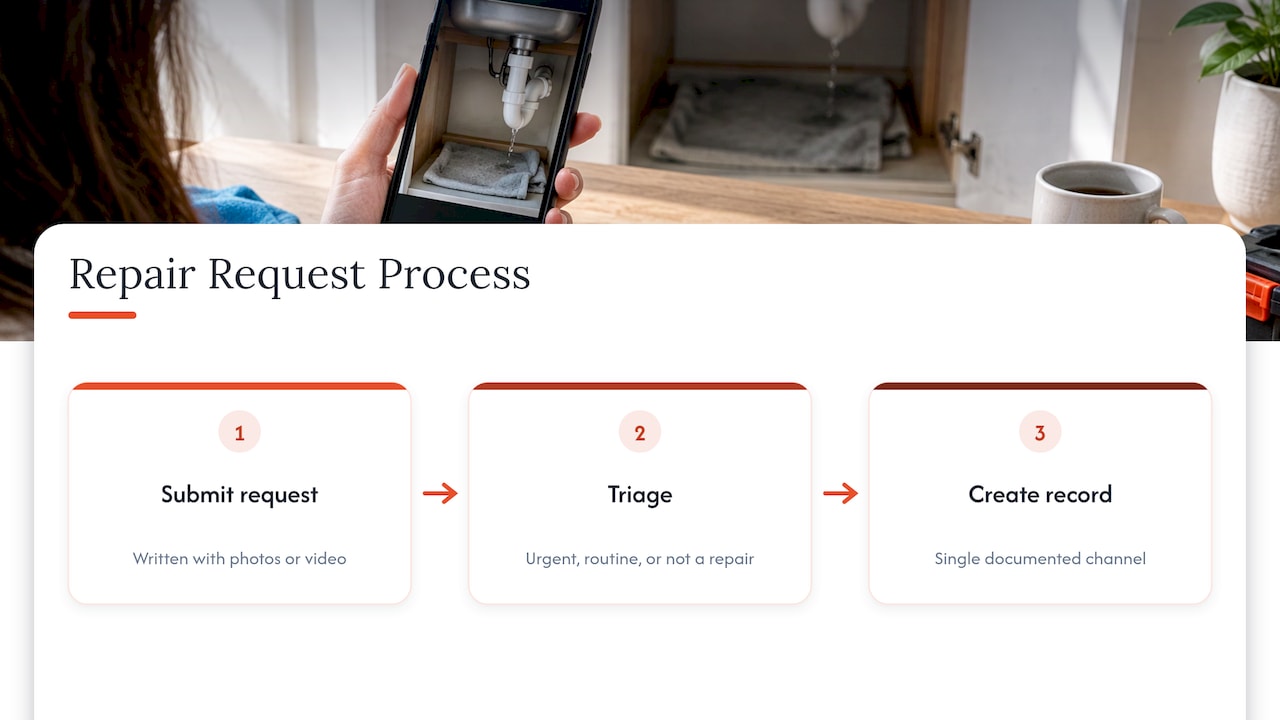
Tell tenants exactly how to report a problem, and accept it only that way. A written request with photos or video lets you or your coordinator triage quickly: urgent, routine or not a repair at all. Text threads and phone calls get lost. A single documented channel creates a record you can use later.

Repair request submission and three-way triage

Define emergencies in writing

An emergency plan should answer these questions before anything happens:

  • What counts as an emergency (active leak, no heat in winter, gas smell, loss of power, security issue)?
  • Who does the tenant call, and who answers after hours?
  • Which vendors are on call at night?
  • How much can the local contact spend without your approval?
  • When do you need to hear about it?

Put this in the lease package so tenants know it from day one. Our emergency maintenance protocol shows how we structure it, and our post on the three kinds of maintenance a rental will need helps you budget for routine, preventive and emergency work.

Know what you owe the tenant

Distance doesn’t change your obligations. HUD’s tenant-briefing examples list owners as responsible for maintaining common areas, keeping appliances in working order, making necessary repairs and complying with health, housing and building codes, as shown in HUD’s tenant briefing exhibit. That exhibit comes from HUD’s housing program materials, so check your own state and city rules for how they apply to a private lease.

Inspect on a schedule

Schedule documented inspections with your local contact: a move-in inspection, periodic checks and a move-out inspection. Use the same checklist each time and require dated photos. Those photos protect you when a security deposit is disputed and show you the property’s condition without a trip.

Software and communication habits that keep you in control

Technology doesn’t replace local people, but it makes the distance manageable. A good setup lets you see rent status, open maintenance requests, expenses and documents in one place, ideally without relying on your memory.

A few habits matter more than any specific tool:

  • Pick one channel for each type of communication and stick to it.
  • Respond within a set window. Tenants and vendors judge you by speed.
  • Keep a log. Note every repair, call and decision with the date.
  • Review monthly. Once a month, look at income, expenses, open repairs and upcoming lease dates.
  • Give tenants a portal. An online tenant portal for payments and requests keeps everything in one place.

Laws and taxes to check before you go remote

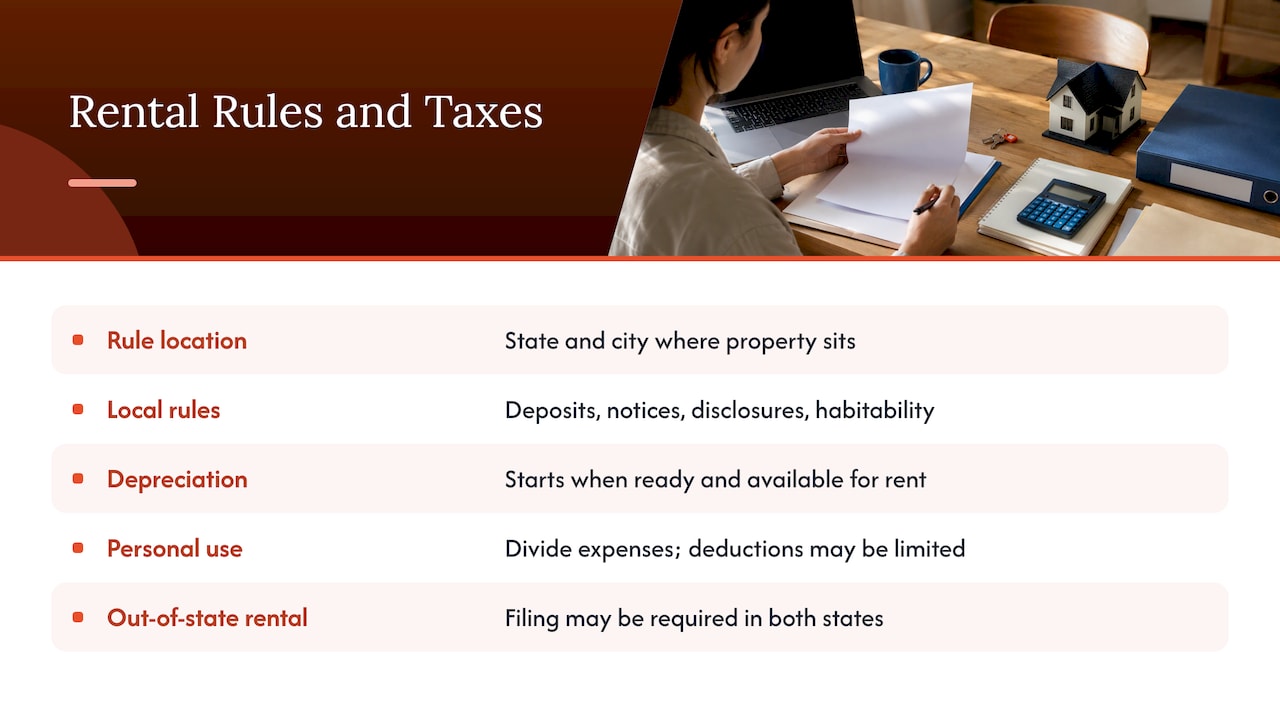
This part depends on where the property sits, not where you live. Landlord-tenant rules differ by state and often by city, covering security deposit handling, notice periods, required disclosures and habitability standards. Review the rules in the state where the rental is located, and speak with a local attorney before you draft a lease or serve any notice.

On taxes, rental income is reported as income and certain costs can be deducted. The IRS explains in Publication 527 that depreciation is a capital expense used to recover the cost of an income-producing property over its expected life, and it can begin once the property is ready and available for rent. The same publication says that if you use the property personally, you must divide expenses between rental and personal use, and your deductions may be limited. That 2020 edition is the version we’ve reviewed, so confirm the current rules with the IRS or a CPA before filing. If you live in a different state from your rental, a tax professional can tell you whether you have filing obligations in both.

Laws and taxes to check before you go remote

When self-managing from afar stops making sense

Many owners start by self-managing and it works until it doesn’t. Common signals that it’s time to hand off the on-site layer:

  • You’re making repair decisions without being able to see the problem.
  • Vendor calls keep pulling you away from your job or family.
  • You own more than one property, or a multi-unit building.
  • Turnover is rising and vacancy is costing you.
  • You’d rather own the asset than run it.

Handing off doesn’t mean giving up control. A good manager reports to you, but handles tenants, vendors, inspections and compliance on the ground. If you’re an investor adding properties across markets, the same logic applies at larger scale. Our post Built by Investors, for Investors explains how we think about it.

Our perspective on remote ownership

We’ve worked with owners who live across town and owners who live across the country. The ones who feel least stressed share one trait: they stopped treating distance as the problem and built a system around it.

Our approach is built on a pod-based team structure, so the people who know your property and your tenants are the same people answering your calls. We keep maintenance in-house, which means fewer unknowns when a repair comes in. We choose vendors transparently, so you can see why a contractor was picked. We also focus on resident retention, because a tenant who stays is the cheapest, calmest form of income a remote owner can have.

After more than 15 years and 2,700 properties served across 10 regional markets, we’ve come to a simple view: you shouldn’t have to choose between owning real estate and having a life. Our goal is for you to see clear numbers and make the big decisions, while our team handles everything that needs a person on site.

MediaBeast

Let us handle the on-site work

If you own a rental in one of our markets and don’t want to coordinate vendors, inspections and tenants from a distance, our property management service covers leasing and tenant placement, rent collection, maintenance and ongoing resident care. We work in Charleston and Columbia, SC, Fort Worth and Dallas-Fort Worth and Houston, TX, Kansas City and Overland Park, and Jacksonville and Jacksonville Beach, FL. Investors with larger plans can also look at our asset management and multifamily and build-to-rent services.

Aubenrealty

Tell us about your property and we’ll explain how management would work for it. Start at aubenrealty.com.

FAQ

Can I really manage a rental in another state by myself?

Yes, many owners do. Marketing, screening, leasing, rent collection and bookkeeping can all be handled online. What you can’t do remotely is physical work, so you need a reliable local contact and vetted vendors for repairs, inspections and emergencies.

What is the biggest risk for a remote landlord?

Slow or poorly informed responses to maintenance problems. Without someone who can see the unit, small issues grow into expensive ones. A written request process, an emergency plan with spending limits and primary and backup vendors reduce that risk.

Do fair housing rules still apply if software screens my tenants?

Yes. HUD’s 2024 guidance says housing providers stay responsible for discriminatory decisions even when an automated service made the recommendation. Use written criteria, apply them consistently and review the underlying report yourself.

Should I use a property manager or hire a local helper?

A local helper can cover a single property with light needs. A property manager makes more sense when you have several units, want after-hours coverage, or don’t want to coordinate vendors and compliance yourself. Choose based on how much on-site work you want to oversee.

Sources

Rental Owner Onboarding: What Happens After You Hire a Manager

Rental owner onboarding is the stretch between saying yes to a property manager and the day your home is rented, or your existing tenants are fully handed over, under that manager’s care. It covers the agreement, your documents, a property walkthrough, a rent and market review, the setup of money and records, and a clear map of who decides what. Done well, it takes a few focused conversations from you and then gets out of your way.

This guide walks through each stage in order, explains what to have ready, and shows where owners most often lose time. It is written for investors adding a property, homeowners renting out a house for the first time, and anyone comparing how managers start a relationship.

Aubenrealty
Make Rental Ownership More Manageable
Auben Realty provides property management, renovation, and tenant placement services for owners seeking less hands-on involvement.

Explore property management

TL;DR

  • Onboarding runs in a fixed order: discovery conversation, agreement, document and key handover, walkthrough and rent analysis, financial and tenant setup, then launch.
  • Most delays come from missing paperwork, unclear repair approval limits and an unfinished property, not from the manager.
  • Before you sign, settle three numbers: the repair approval ceiling, the reserve balance and the reporting schedule.
  • Pre-1978 homes carry federal lead paint disclosure duties, so ask your manager how they handle them.
  • A completed intake form on day one is the single best way to shorten the process.

Table of Contents

What owner onboarding actually covers

Hiring a manager does not make you a passive bystander. Fannie Mae’s guide for new landlords notes that a manager’s duties may include marketing units, selecting tenants, maintaining the building, budgeting, tenant relations and collecting rent, and that the owner remains responsible for hiring and supervising the manager. Onboarding is where that supervision is set up: you define what the manager does, what they may spend, and what you see every month.

Think of it as five jobs happening in parallel:

  1. Legal setup: the management agreement, tax forms, insurance details.
  2. Property knowledge: keys, access, systems, warranties, known quirks.
  3. Market positioning: the rent, the condition standard, the leasing plan.
  4. Money and records: accounts, owner statements, reserves, vendor payments.
  5. Tenant handoff: existing leases and deposits, or a marketing plan for a vacant unit.

A vacant home skips the last handoff and goes straight into leasing. A rented home skips marketing but needs more records. Either way, the five jobs are the same.

Step 1: The discovery conversation

The first call is about your goals, not the paperwork. A good manager asks what you want from the property: steady monthly cash flow, appreciation, a hands-off hold while you live elsewhere, or a build-to-rent position inside a larger portfolio. Your answer shapes everything from the rent strategy to how quickly you want repairs approved.

Come ready to answer:

  • Is the property vacant, owner-occupied or already leased?
  • Is there a mortgage, an HOA or a ground lease with rules about renting?
  • What is your target rent, and what is the minimum that covers your costs?
  • How much do you want to be consulted on repairs and tenant decisions?
  • Are you planning improvements before leasing?

If you are weighing whether you need a full manager or only leasing help, our overview of what a property manager will do for you lays out the day-to-day scope.

Step 2: The management agreement

The agreement is the most important document in onboarding because it fixes the boundary between your role and the manager’s. Read it slowly. The items below deserve a line-by-line check.

Authority and spending limits

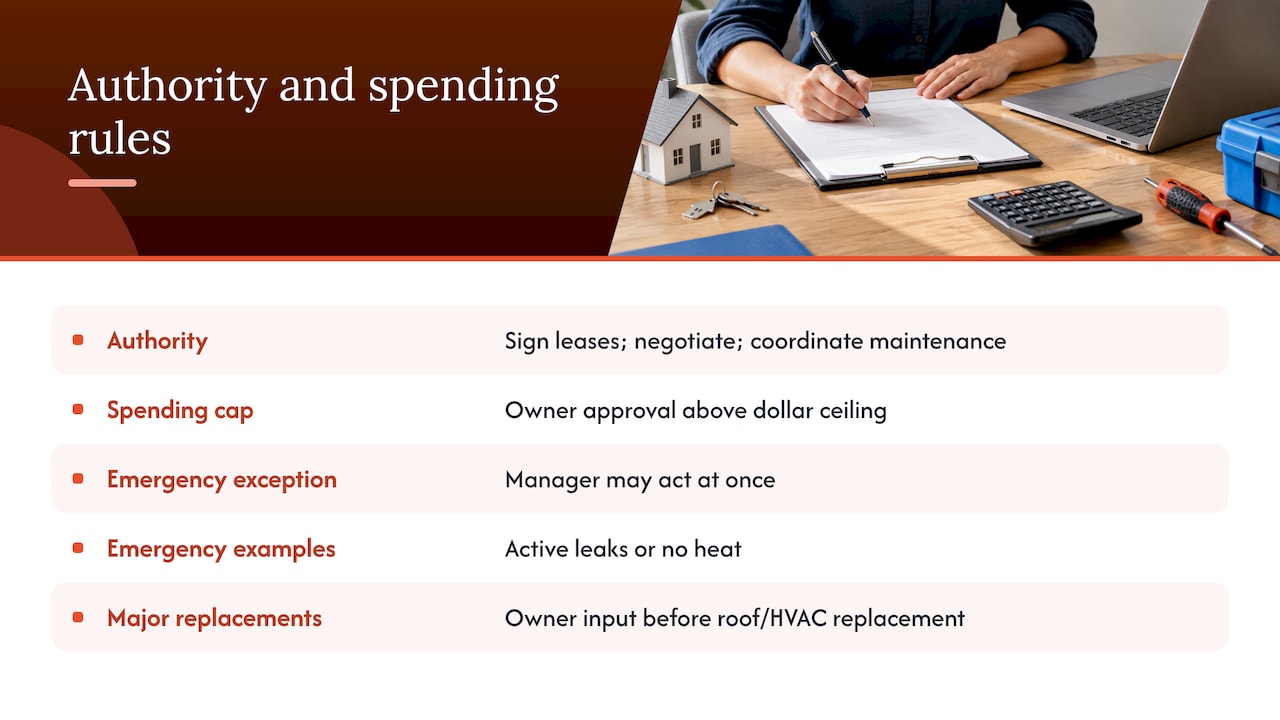
The agreement should state whether the manager may sign leases, negotiate rental terms and coordinate maintenance on your behalf. It should also set a dollar ceiling above which the manager must ask you before spending. There is no universal number: a small single-family rental and a 40-unit building need different limits. Pick a figure that lets a broken water heater get fixed the same day without a phone tag, and that gives you a say before a roof or HVAC replacement. Emergencies, such as active leaks or no heat, are usually carved out so the manager can act at once. Make sure the agreement says so.

Authority and spending limits

Fees

Management arrangements generally combine a monthly management fee with other charges such as a leasing fee and maintenance coordination fees. Ask for every fee in a single schedule so you can model your net return. Our fees depend on the property type and market, so we quote them for your specific home or portfolio rather than publishing one number.

Reporting and accounting

Confirm that you will receive monthly owner statements showing income, expenses and any reserve balance, and agree on how you access them. Look for specific duties listed in the agreement, so both sides know where the manager’s job ends and yours begins. Vague language such as “general management” is where disputes start.

Term and exit

Check the length of the agreement, how either side can end it, any termination fee, and what happens to tenant deposits and records when it ends. A manager confident in the service will not hide these terms.

Because rules for licensing, trust accounts and contract contents vary by state, treat any checklist as a starting point. For legal questions about your contract in your state, ask a real estate attorney licensed there.

Step 3: Documents and information to prepare

The fastest onboardings are the ones where the owner arrives with a folder. Gather these before or right after signing.

Category What to have ready
Ownership Deed or proof of ownership, entity documents if you hold title through an LLC, your tax ID and a completed W-9
Insurance Landlord or dwelling-fire policy declarations page, with your manager listed as needed
Property history Year built, age of roof, HVAC and water heater, recent repairs, known issues
Access All keys, garage openers, gate codes, lockbox details, smart-lock logins
Warranties and manuals Appliance and system warranties, home warranty plan if any
Rules HOA documents, rental restrictions, parking and pet rules, city rental registration or permit requirements
Existing leases Signed leases, addenda, deposit amounts and where they are held, tenant contact details, payment history
Banking Account details for owner payouts
Preferences Pet policy, smoking policy, preferred vendors, who may enter the property

We publish a property intake form that captures most of this in one pass. Filling it out before the walkthrough means the visit can focus on the home itself instead of collecting basics.

Pets and special policies

Decide your pet policy early, because it changes your tenant pool and the screening criteria used at placement. Our post on property management and pets walks through the trade-offs so you can set the rule before listing day.

Federal disclosure for older homes

If your home was built before 1978, the EPA’s lead-based paint rule applies. The Lead-based Paint Disclosure Rule requires landlords and property managers to give specific information about known lead-based paint and hazards before a renter signs a lease, with a few exemptions such as housing certified lead-paint free. Tell your manager what you know about the home’s paint history and any past testing so the right disclosure goes into the lease packet.

Step 4: The property walkthrough

The walkthrough is where a manager turns your paperwork into a plan. Expect a detailed, room-by-room visit that is documented with dated photos and notes. That record later protects you when a security deposit is discussed.

What gets checked:

  • Condition of finishes: flooring, paint, walls, fixtures, windows and screens.
  • Major systems: HVAC age and filter condition, water heater, plumbing under sinks, electrical panel, smoke and carbon monoxide detectors.
  • Exterior: roof and gutters, drainage, fencing, landscaping, irrigation, driveways, any pool or outdoor structures.
  • Safety items: handrails, stairs, locks, lighting and egress. If children will live in the home, stairs are a common concern; some tenants look into stair childproofing options for renters, and it helps to decide up front what modifications your lease allows.
  • Make-ready list: what needs to be repaired, cleaned or replaced before photos are taken.

The outcome should be a written list divided into three groups: must fix before leasing, worth doing for better rent, and can wait. If the work is larger than touch-up, a renovation oversight service can scope bids and supervise contractors so you are not managing a crew from afar. We cover that under project management.

Step 5: Rent analysis and leasing plan

A rental market assessment compares your home to similar properties nearby that are active or recently leased, adjusting for size, condition, amenities and location. It should give you a recommended rent and a realistic range, plus an expected time to lease at each price point.

Ask to see how the number was built. A good analysis shows the comparable homes, not just the conclusion. Then agree on:

  • The listing price and the date you will review it if there are no applications.
  • Screening criteria: income multiple, rental history, credit and background standards, applied consistently to every applicant.
  • Lease term and target move-in window. Many owners aim for a lease that expires in a stronger leasing season in their market.
  • Marketing channels and photography.

Fair housing law applies to every step of tenant selection, so consistent written criteria protect both you and the manager.

Step 6: Setting up money, records and maintenance

This stage is the quiet backbone of the arrangement, and it is where a manager’s systems matter most.

Payments and reserves

You will typically agree on a reserve balance the manager holds for routine repairs, so small costs do not need a fresh transfer each time. You also set the payout schedule and confirm the payout bank details. Tenant security deposits are handled according to your state’s rules, so ask where they will be held and who is responsible for the return and accounting.

Owner portal and statements

Most owners prefer to see activity without calling. Make sure you receive portal access, know where to find statements, and understand how repair invoices and tax documents are delivered. At Auben, owners get access through our owner portal.

Maintenance setup

Agree on how requests come in, who triages them, and how vendors are chosen. Ask whether the manager has in-house maintenance, how outside vendors are selected, and whether you can request bids above your approval ceiling. Our approach uses in-house maintenance with transparent vendor selection, so you can see what was done and why.

Tenant records

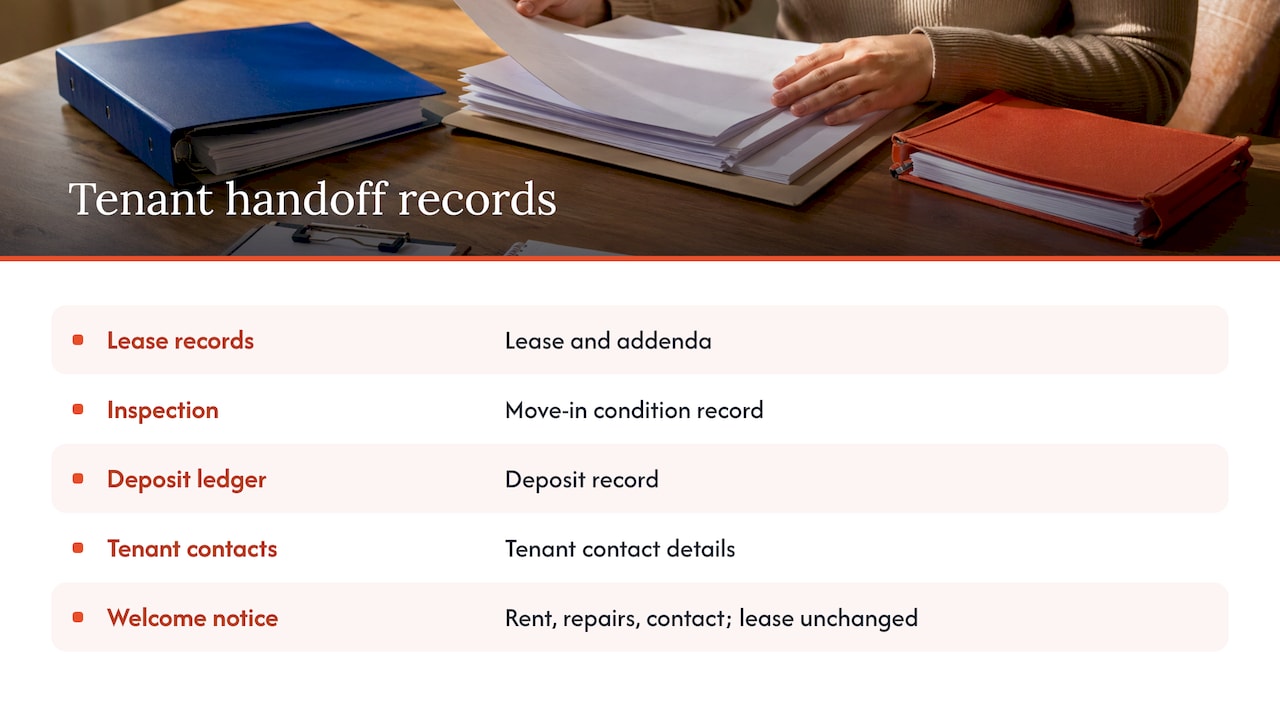
For an occupied property, the manager collects the lease, addenda, move-in inspection, deposit ledger and contact details, then introduces themselves to the tenants with a welcome notice that explains where to pay rent and how to submit a maintenance request. The tenants should hear a single, clear message about the change: new payment instructions, a new contact and an unchanged lease.

Five groups of records in a tenant handoff

How long onboarding takes and what slows it

There is no standard clock. Timing depends on whether the home is vacant, how much repair work is needed, and how fast documents arrive. The common sources of delay are the same everywhere:

  • Missing documents: a lost lease copy, an absent W-9 or unavailable HOA rules.
  • Unresolved access: keys with a previous manager or a tenant who is not told about the change.
  • Make-ready work: repairs that take longer than the leasing plan assumed.
  • Open approvals: no agreed spending ceiling, so every small repair waits for an email reply.
  • Slow decisions on rent: holding out for a number the market comparables do not support.

Owners who control these five things control most of the timeline. A well-run manager will give you a written checklist with owners and dates, so you can see what is waiting on whom.

Switching from a previous manager

If you are moving a rented property from another manager, add a transition plan. Give written notice according to your current agreement, request the full file (leases, ledgers, deposits, inspection reports, vendor contacts and keys), and confirm the date deposits are transferred. Have the new manager send tenants the new payment instructions before the first rent date so no payment goes to the wrong place.

Our perspective

Owners tell us the same thing after the first month: the agreement was the easy part, and the first 30 days were what shaped the relationship. We design onboarding so that you know who is responsible for what before the first repair request arrives.

At Auben, we combine local market expertise with investor-focused strategies. A pod-based team structure means a focused group handles your property, rather than a queue of unrelated staff. In-house maintenance and transparent vendor selection mean that repair decisions are visible to you. Proactive resident retention keeps good tenants longer, which protects your returns.

With more than 15 years of experience and 2,700 properties served across 10 regional markets, we have seen what makes a handoff smooth: complete information, a clear approval limit and honest rent expectations. Give us those three things and our technology and team handle the rest.

MediaBeast

Work with a team that handles the handoff

If you own single-family, multi-family or build-to-rent property in Charleston, Columbia, Fort Worth, Dallas-Fort Worth, Kansas City, Overland Park, Houston or Jacksonville, we can take the onboarding steps above off your plate: agreement, walkthrough, leasing plan and ongoing reporting. Start with our property management page, or see how asset management fits if you hold several properties.

Aubenrealty

If you are still deciding what to ask a manager, our common questions owners have and the post on key factors investors need to track are good places to build your list.

A short owner checklist

  1. Read the whole agreement and confirm the repair approval ceiling, fee schedule and exit terms.
  2. Send ownership, insurance, tax and banking documents.
  3. Hand over every key, code and warranty.
  4. Complete the intake form and share known problems honestly.
  5. Attend or approve the walkthrough list and decide what to fix before leasing.
  6. Review the rent analysis and agree on the screening criteria.
  7. Confirm portal access, reporting dates and payout schedule.
  8. For occupied homes, make sure tenants receive a clear notice about the change.

FAQ

Does onboarding mean I am hired?

Not exactly. Onboarding usually begins after you sign a management agreement, but you are the one who hires and supervises the manager. The discovery call and property review before that are about fit, and you decide whether to sign.

What documents does a manager need from me?

Expect to provide proof of ownership, a W-9, insurance information, keys and access codes, warranties, HOA rules and, for occupied homes, current leases and deposit details. A completed intake form covers most of the property details.

What should I approve during setup?

Approve the management fee schedule, the maximum repair amount the manager can spend without asking you, your reserve balance, your pet and screening policies, and the rent and make-ready plan. Also confirm how and when you receive statements.

Do I need to be at the property walkthrough?

You do not have to be, but your input helps. If you cannot attend, share known issues and past repairs in writing, and review the photos and the make-ready list afterward before approving work.

Do lead paint rules apply to my rental?

They apply to most private housing built before 1978. The EPA requires landlords and managers to provide specific lead hazard information before a lease is signed, so tell your manager the year built and any testing you know about.

Sources

Where to Invest in Kansas City: Best Areas for Rentals

For most rental investors, the best places to invest in Kansas City are the Missouri-side submarkets where purchase prices are still low compared with rent: Independence, Raytown, Blue Springs and parts of Northeast and Midtown Kansas City. Lee’s Summit and Overland Park suit investors who want lower turnover and steadier tenants over a higher yield. The right pick depends on your budget, how hands-on you want to be and how much risk you will carry. Below you will find the numbers by area, the local costs that change your return and a way to compare deals before you buy.

Aubenrealty
Make Kansas City Rentals Easier to Manage
Auben Realty provides property management, renovation, and tenant placement services for investors across its regional markets.

Visit Auben Realty

TL;DR

  • Lower-priced Missouri-side areas (Northeast KC, Midtown, Raytown, Independence) show the highest gross yields in published 2026 guides, but they ask for more inspection and management.
  • Suburbs such as Blue Springs and Lee’s Summit trade yield for school districts, longer tenancies and lower turnover.
  • Property tax, wind and hail insurance and financing terms can move your real return by more than a small rent difference, so underwrite them first.
  • Missouri and Kansas follow different tax and rental rules, so decide which side of the state line you are buying on before you run numbers.
  • The return is made at purchase: price, condition and a realistic expense budget matter more than hoping for rent growth.

Table of Contents

Why investors look at Kansas City

Kansas City draws rental investors because entry prices are modest next to coastal metros while rents are healthy for the price. One 2026 investor guide puts the metro median home price at $280,000 with an average rent of $1,350, and cites cash-on-cash targets of 9% to 11% on below-median Missouri-side purchases. Another market data page lists a median rental rate of $1,249 per month, appreciation of 3.7% a year and rent growth of 3.2% a year for the Kansas City MO-KS market.

The same data shows why you should not buy on a headline. That page also reports a median cap rate of 3.8% across the metro, so averages hide a wide gap between the cheapest and the most expensive homes. An analysis of Kansas City, MO listings found that 93% of listings under $100,000 cash-flow on paper, against 2% at $200,000 to $300,000 with 20% down at a 7% mortgage rate. Price point, not just the city, decides the result.

The metro also spans two states, dozens of suburbs and very different blocks. That variety is the opportunity: you can choose cash flow, stability or a mix, then pick the area that matches.

Kansas City investment areas compared

The table shows typical single-family purchase prices and three-bedroom rents by submarket, as published in a 2026 Kansas City investor guide. Treat them as starting ranges for your own underwriting, not quotes, because prices move by street and by condition.

Area Typical purchase price Typical 3BR rent Gross yield Who it suits
Northeast Kansas City $100K–$145K $1,100–$1,350 10–12% Experienced investors, value-add and BRRRR plays
Midtown / Westport-adjacent $140K–$175K $1,300–$1,550 10–11% Investors targeting an urban renter base
Raytown $150K–$190K $1,350–$1,550 9–10% Cash-flow buyers comfortable with older stock
Independence $160K–$210K $1,450–$1,650 8.5–10% Buyers who want working-family demand
Waldo $200K–$260K $1,600–$1,900 8–9% Buyers who want young-professional tenants
Blue Springs $220K–$290K $1,700–$2,000 7–8% Long-term holds with school-driven demand
Lee’s Summit $270K–$350K $1,900–$2,300 6.5–7.5% Lower turnover, premium suburb

Gross yield is annual rent divided by price, before taxes, insurance, maintenance, vacancy and management. Net returns are lower, which the underwriting section below walks through.

Northeast Kansas City and Midtown: highest yield, most work

These areas show the strongest gross yields in the guide, and they are where buy, renovate, rent, refinance strategies are most often discussed. They also bring the most active management: older houses, more frequent turnover and block-by-block differences. The same investor guide that cites the 9% to 11% targets notes that conditions can vary block by block east of Troost, so walk the street and read the comparable rents, not just the ZIP code.

Midtown and Westport-adjacent homes draw an urban renter base. If you plan to renovate, build the scope and a contingency into your numbers before you offer.

Raytown and Independence: cash flow with working-family demand

Raytown combines modest prices with rents of $1,350 to $1,550, but much of the housing is older, so a thorough inspection of the roof, sewer line, foundation and mechanicals should come before any offer. Independence is described as the clearest cash-flow leader in a September 2026 lender guide, which cites median prices of $170,000 to $220,000, rents of $1,100 to $1,400 and cap rates of roughly 6.5% to 7%, with some stabilized properties reaching 7% to 8%. Tenant demand there is tied to logistics and healthcare employment.

Note that guides differ on rents and yields for the same area. That is normal. Use ranges, then confirm with current listings and rent comparables for the exact street.

Waldo, Blue Springs and Lee’s Summit: stability over yield

Waldo attracts young professionals. Blue Springs is known for well-rated schools and long-term tenants. Lee’s Summit is the premium suburb in the table, with the lowest yield and, according to the guide, lower turnover. Lower turnover is worth real money: every month of vacancy and every re-leasing cycle costs rent, cleaning, repairs and leasing fees.

If you are a first-time investor or an out-of-state owner, these areas often pair better with hands-off ownership, because tenants stay longer and houses are newer.

Missouri side or Kansas side

Overland Park, Olathe and Leawood sit in Johnson County, Kansas, and generally come with higher prices than the Missouri-side areas above. They follow Kansas rules rather than Missouri rules for property tax and landlord-tenant matters, so build a separate budget for each side. If you are weighing both, our Kansas City market page is a good place to start.

Costs that change your return

The table above ends at gross yield. Four local costs decide what you keep.

Property taxes

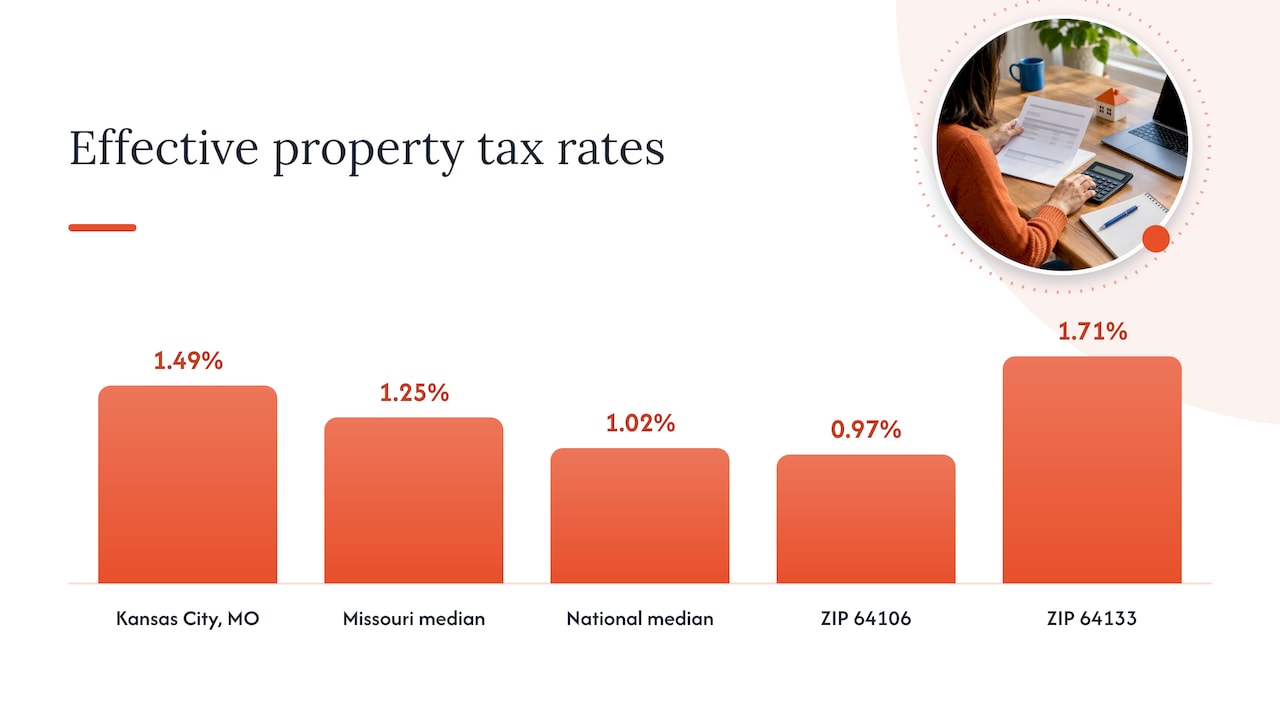
Kansas City, Missouri has a median effective property tax rate of 1.49%, above the Missouri median of 1.25% and the national median of 1.02%, and rates by ZIP run from 0.97% in 64106 to 1.71% in 64133, driven by school district levies and local taxing districts. On a $180,000 house, the gap between those two ZIP codes is more than $1,300 a year.

Jackson County has also seen sharp reassessments. One investor guide notes recent cycles with valuation jumps of 30% or more and recommends underwriting a higher tax bill and reviewing every assessment notice so you can file an appeal on time. Build that cushion into your numbers on every Jackson County purchase.

Property taxes

Insurance

Kansas City sits in an active hail and tornado corridor. A 2026 insurance comparison page reports average landlord insurance in Missouri at $2,809 per year and notes that percentage-based wind and hail deductibles are increasingly standard on Missouri policies. That means you should know your deductible in dollars, not just the premium, and keep a cash reserve to cover it. Roof age and condition affect both underwriting and your claim outcome, so a new or recently replaced roof is worth paying for. When you compare landlord insurance coverage, look at dwelling coverage, loss of rents, liability and the wind and hail terms side by side.

Financing

Investment loans cost more and need more cash than owner-occupied loans. A July 2026 lender guide describes standard purchase leverage of 75% to 80% loan-to-value, with some strong files reaching 85%, reserves of around six months of the full monthly obligation and credit-score tiers from a 620 floor to a 700 threshold for the highest-leverage programs. Its example: a $195,000 house renting for $1,500 a month at 80% LTV produces debt-service coverage of roughly 1.15x to 1.20x. Terms vary by lender and change with rates, so get current quotes before you fix a budget.

Maintenance and winter wear

Older houses in the metro face freeze-thaw cycles, so plumbing, roofs and drainage deserve attention at inspection. Budget for capital items such as roofs, HVAC and water heaters separately from monthly repairs, and your cash-flow estimate will hold up better.

Downspout directing meltwater away from rental foundation

Rental rules to know before you buy

In Kansas City, Missouri, rental housing has its own permit and inspection regime. According to the Kansas City Health Department, a person may not offer a unit for rent without a valid rental permit. Inspections follow complaints and also happen as random annual routine inspections, and occupied units can be inspected only in exigent situations or with at least five days’ notice to the tenant. Bring a unit up to code before you list it, and confirm the current permit process with the city.

Kansas City, Kansas and the Johnson County suburbs have their own local requirements. Check the municipality where the property sits before you close, because a house a few blocks across a city line can follow different rules. For lease terms, security deposits and notice periods, rely on the state statutes and a Missouri or Kansas attorney, not on a general template.

How to compare a deal before you buy

A clear process keeps you from buying the yield in a brochure. Run every deal through the same steps.

  1. Start with the purchase price. The investor team behind one 2026 guide argues that in Kansas City the lever is the price, not the rent, because rents are anchored by what working families can pay. The return is made at the buy, when a seller faces a reassessment, an older roof or a vacant unit.
  2. Estimate realistic rent. Use three current comparables for the same bedroom count, condition and street, not an area average.
  3. List operating costs. Property tax at the ZIP’s effective rate, insurance with wind and hail terms, maintenance, vacancy, management and leasing fees.
  4. Add capital reserves. Roof, HVAC, water heater, sewer line and flooring, set aside monthly.
  5. Test the financing. Run the loan at today’s rate and again at a higher rate, and confirm that debt-service coverage stays above your lender’s minimum.
  6. Stress the downside. Two months of vacancy, a 30% tax reassessment and a $5,000 repair. If the deal still works, it is a real deal.

Here is a worked example with deliberately round numbers. A house bought at $190,000 renting for $1,500 produces $18,000 of annual rent, a 9.5% gross yield. Property tax at 1.49% is about $2,830, and insurance near $2,809 brings those two costs to roughly $5,640. Before maintenance, vacancy and management, you are already at about $12,360 of operating income. That is how a 9.5% gross yield becomes a lower net figure, and why the process above matters.

Which area fits which investor

  • Cash-flow focused, comfortable with renovation: Northeast KC, Midtown, Raytown.
  • Balanced return with working-family demand: Independence.
  • Long hold with low turnover: Blue Springs, Lee’s Summit, and Johnson County suburbs on the Kansas side.
  • Scale and portfolio plays: multifamily and build-to-rent, where professional management and a clear asset plan matter most.
  • First-time and out-of-state investors: start in a newer or recently renovated house in a stable suburb and hire local management from day one.

Our perspective: buy well, then run it like a business

We have spent more than 15 years managing homes for owners and investors, and our team has served 2,700 properties across 10 regional markets, Kansas City among them. What we see over and over is that the area you choose matters less than how you buy and how the property is run afterward.

A strong Kansas City deal starts with a price that leaves room for taxes, insurance and repairs. After that, results come from day-to-day operations: how fast a unit is leased, how well residents are kept, how maintenance is handled and how clearly the owner sees the numbers.

That is why we built Auben around local market expertise combined with investor-focused strategies. Our pod-based team structure gives each owner a focused group that knows the portfolio. In-house maintenance and transparent vendor selection help keep repair costs and quality visible. Proactive resident retention and technology-enabled reporting support the long-term returns investors are after.

Our advice to a first-time Kansas City investor is simple: pick the area that fits your tolerance for hands-on work, underwrite conservatively and put management in place before you close, not after the first vacancy.

MediaBeast

Work with Auben in Kansas City

Auben Realty is a full-service real estate investment and property management firm. If you are choosing where to buy, our brokerage services team can help with acquisition and sales, and our property management team handles leasing, tenant placement, maintenance and day-to-day owner reporting. For larger portfolios, we offer asset management and multifamily and build-to-rent services.

Aubenrealty

Renovating before you rent? Our project management service oversees scope and vendors so the work stays on budget. Talk to us through the Kansas City management page, and see what a managed rental looks like in our Kansas City homes for rent. You can also read our view on why Kansas City works for cost and livability.

FAQ

What is the best area to invest in Kansas City for cash flow?

Published 2026 guides show the highest gross yields in Northeast Kansas City, Midtown, Raytown and Independence, with ranges from roughly 8.5% to 12% before expenses. These areas usually need more inspection and more active management. Compare net numbers after taxes, insurance and repairs, not gross yield alone.

Is Kansas City a good market for first-time investors?

It can be, because prices are moderate and rents are healthy for the price. First-time investors often do better in stable suburbs such as Blue Springs or Lee’s Summit, or in a renovated house in Independence, and with professional management from the start. Run the stress test above before you commit.

How much are property taxes on a Kansas City rental?

The median effective rate in Kansas City, Missouri is about 1.49%, with ZIP codes ranging from 0.97% to 1.71%, according to the tax data above. Reassessments in Jackson County have been large, so budget for a higher bill and review every notice for appeal deadlines.

Do I need a permit to rent out a house in Kansas City, Missouri?

Yes. The city’s health department states that a unit may not be offered for rent without a valid rental permit, and units can be inspected after complaints and on a random annual basis. Confirm current steps and fees with the city before listing.

Sources

Where to Invest in Charleston: A Guide for Overland Park Investors

If you live in Overland Park and are looking at Charleston, South Carolina, the practical answer is this: invest in the Charleston submarket that matches your strategy and your tolerance for hands-off ownership, then measure it against what your own backyard already offers. Charleston’s appeal is a deep renter pool, coastal demand and limited land. Overland Park’s appeal is a stable, undersupplied suburb you can drive to. Neither is automatically better. The right choice depends on price per door, tax treatment, and who manages the property when you are 1,000 miles away.

This guide walks through how Overland Park looks on the numbers, how to think about Charleston’s submarkets, and how to buy and run an out-of-state rental without becoming a full-time landlord. We manage and broker properties in both Charleston and the Kansas City area, so we write from both sides of that comparison.

Aubenrealty
Manage Charleston Investments Remotely
Auben Realty provides property management, renovation, and tenant placement services for investors seeking a more hands-off ownership experience.

Explore Auben Realty

TL;DR

  • Start with your strategy: cash flow, appreciation or build-to-rent. Each points to a different part of Charleston, and a different part of Overland Park.
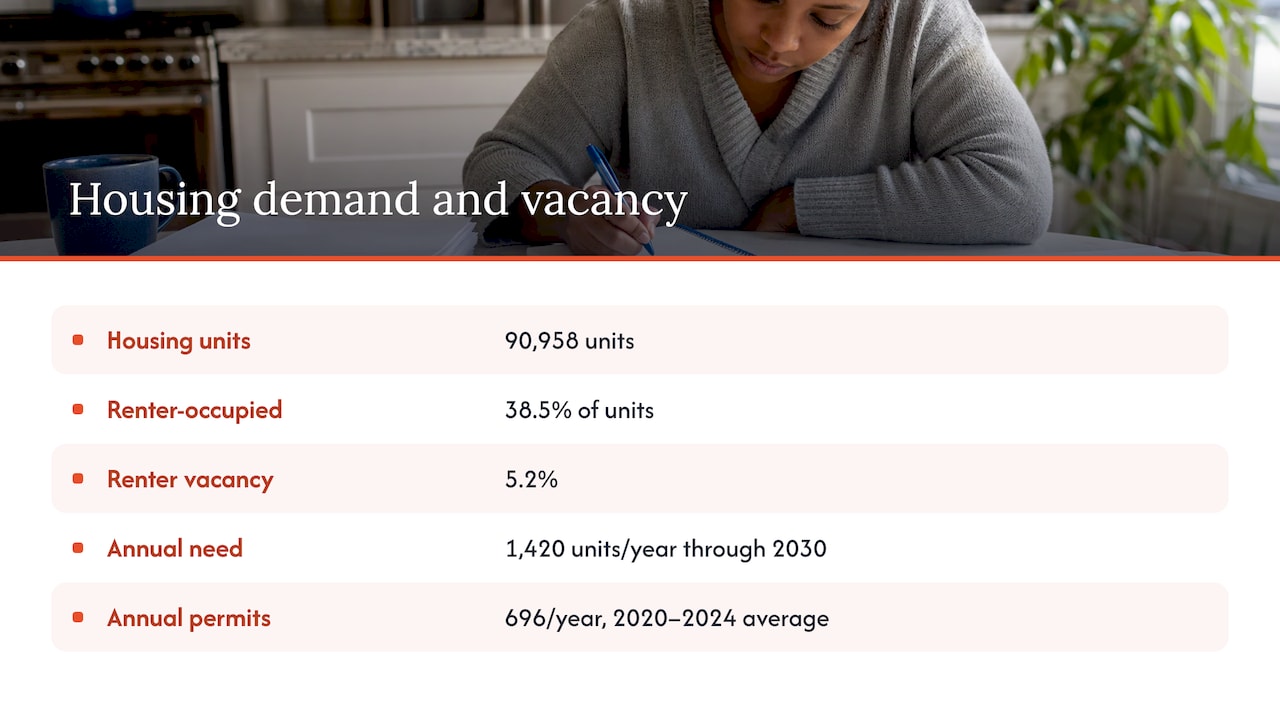
  • Overland Park is a strong benchmark: rental vacancy near 5.2% and a housing supply gap support demand, but entry prices are high and some ZIP codes cash flow poorly.
  • In South Carolina, non-owner-occupied property is generally taxed at a higher assessment ratio than a primary home, so underwrite taxes before you fall for a listing.
  • Buying remotely works when you have a local manager, a renovation overseer and a clear exit plan in place before closing.
  • Run the same checklist on every deal in both cities, and compare after-tax, after-vacancy returns, not headline cap rates.

Table of Contents

Start with the Overland Park baseline

Before you ship capital 1,000 miles, know what your home market gives you. Overland Park is a useful yardstick because it is well documented and because many Kansas City-area investors already hold property here.

What Overland Park costs and rents for

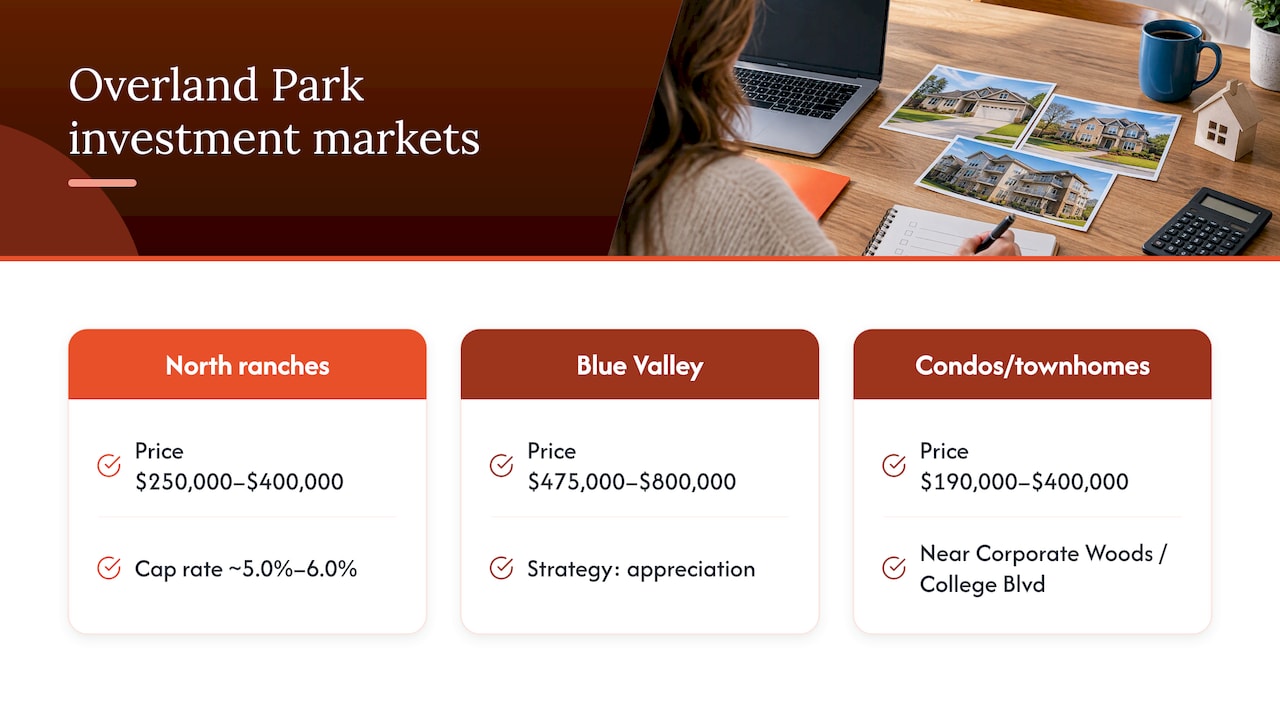
Prices are high for the Midwest. As of October 2026, the median listing price was $717,715 and the median sold price $540,000, with median rent at $2,200 a month. Those are city-wide figures, and the city is really several markets. A published investment guide describes mid-century ranches in North Overland Park at $250,000 to $400,000 with cap rates of roughly 5.0% to 6.0%, Blue Valley single-family homes at $475,000 to $800,000 pitched at appreciation, and condos and townhomes near Corporate Woods and College Boulevard at $190,000 to $400,000.

Treat guide-level cap rates as a starting point only. A ZIP-level yield calculation for 66223 shows how fast the math changes once financing enters: a typical price of $503,000 against typical rent of $2,036 a month produced negative monthly cash flow at an 8.03% interest rate with 25% down. High-priced Blue Valley homes are appreciation plays, not cash-flow plays.

What Overland Park costs and rents for

Why demand holds up

The city’s own Housing Needs Analysis estimates 90,958 housing units, 38.5% of them renter-occupied, with a renter vacancy rate of 5.2% and owner vacancy of 0.6%. It says the city needs about 1,420 new units a year through 2030 but permitted only 696 a year from 2020 to 2024. That structural gap is good for landlords already in the market.

Overland Park housing demand and supply figures

The flip side is cost. According to one rent data provider, 42.8% of renter households pay at least 30% of income toward rent, which limits how hard you can push rents.

Taxes in Kansas

The effective property tax rate in Overland Park is about 1.17%, below the Kansas median of 1.40% and above the national median of 1.02%. The Overland Park Chamber of Commerce lists 2025 certified mill levies of 14.538 for the city, 17.286 for Johnson County and 53.596 for the Blue Valley school district. Those numbers become your tax line in any pro forma.

How to think about Charleston

Charleston is a coastal, supply-constrained metro. Water, marsh, historic districts and conservation limits cap how much can be built, and that is the root of the demand story. Investors generally sort the region into a few groups.

Area type Typical strategy What to underwrite closely
Peninsula and historic downtown Appreciation, premium long-term rentals Entry price, flood zone, historic-district rules on renovation
Mount Pleasant and the east side Family single-family rentals, appreciation School zones, insurance, HOA rules
West Ashley and James Island Value-add and renovation, mid-priced rentals Age of the house, drainage, renovation scope
North Charleston and the Summerville corridor Cash flow, build-to-rent, newer construction Tenant quality, new supply nearby

Treat that table as a map for your own research, not a ranking. Prices and rents move quickly, and we publish our current read on Charleston rents, occupancy and outlook so you can check the latest before you commit.

Match the area to your strategy

Cash flow. Look at mid-priced single-family homes and small multifamily in the less expensive parts of the metro, where the rent-to-price ratio is better. You trade some appreciation for income.

Appreciation. Premium areas rarely cash flow strongly on a financed purchase, in Charleston or in Overland Park’s Blue Valley. You are buying scarcity. Hold periods should be long and reserves generous.

Value-add. Older houses that need work can be bought below the neighborhood’s finished value, renovated and rented. This is the same logic as buying a North Overland Park ranch, just on the coast. Renovation oversight matters most here, because a contractor you cannot visit weekly is your biggest risk. Our write-up on turning houses for rent in Charleston into investment opportunities covers how that works in practice.

Build-to-rent and multifamily. Newer communities with professional management suit investors who want scale and fewer repair surprises. Our Multifamily & Build-to-Rent Services team works with owners on exactly this product type.

Overland Park versus Charleston: how to compare

A fair comparison uses the same inputs on both sides. Do not compare Charleston’s gross rent to Overland Park’s net.

  1. Purchase price and closing costs. Use an actual listing or recent sale in each submarket, not a city-wide median.
  2. Realistic rent. Use the rent of comparable leased homes, not asking rents. Overland Park data sources disagree widely: one reports recent-lease rent of $1,557 in July 2026, another an average rent of $1,280 and gross yield of 5.2% a month earlier. If sources for one city differ that much, verify with leased comps before trusting any figure.
  3. Property taxes. In Kansas, use the mill levy for the exact taxing district. In South Carolina, check the assessment ratio, because a rental generally does not get the lower ratio that an owner-occupied primary residence does. Confirm the current rate with the Charleston County assessor before you underwrite.
  4. Insurance. Coastal wind, flood and homeowners coverage can be a far larger line in Charleston than in Johnson County. Get quotes before you offer.
  5. Vacancy and turnover. Assume more than zero. Budget a month or more of vacancy a year and a turnover cost every lease.
  6. Management fees and maintenance reserve. Include them from day one, even if you plan to self-manage at first.

The after-tax effect is bigger than most first-time investors expect. A commercial analysis for Overland Park shows a 6.05% market cap rate compressing to about 4.88% once the tax load is carried. The same discipline applies in South Carolina, where the tax treatment of non-owner-occupied property deserves a line of its own.

Buying out of state without losing control

Most Overland Park investors who buy elsewhere stumble on logistics, not on math. These are the steps that keep a remote purchase on track.

  1. Pick the strategy first, then the neighborhood. Decide whether you want income, growth or a project before you open a listing site.
  2. Line up a local team before you offer. You need a buy-side agent or brokerage, an inspector, a lender who knows the market, and a property manager who will tell you what rent the house really commands.
  3. Order a thorough inspection. In a humid coastal climate, roof, drainage, moisture and HVAC deserve extra attention. Our guide to rental property inspections explains what to check.
  4. Price the renovation before closing. Get written bids. If work is needed, have someone on the ground oversee it.
  5. Set a lease-up plan. Know who markets the home, screens tenants and signs the lease the week you close.
  6. Plan the exit and the tax picture. Depreciation, capital gains and exchanges all affect what you keep. We cover rental property depreciation, capital gains on rental property and the 1031 exchange in separate guides. Your CPA should confirm how they apply to you.

Financing a long-distance purchase

Conventional investment loans use your personal income. Some lenders also offer DSCR loans, which qualify the deal on rental income instead. One lender describes typical DSCR ratios of 1.10 to 1.25, credit scores of 620 to 660 and down payments of 20% to 25% for investors in Overland Park. Terms vary by lender and change with rates, so get written quotes for the specific property and compare them against your own deal math.

What the Overland Park numbers teach about Charleston

Three lessons carry across.

Submarkets beat city averages. Overland Park has roughly 65 neighborhoods with median prices running from about $243,000 in Quivira Falls to over $1,100,000 in Mills Farm. Charleston’s spread between the peninsula, the islands and the inland suburbs is just as wide. A city median tells you almost nothing about your deal.

New supply is a timing risk. Johnson County had 4,396 new housing units permitted between September 2025 and August 2026, which competes for the same tenants. Ask the same question in any Charleston area you like: what is being built within two miles, and when does it deliver?

Short-term rental income is not long-term income. AirROI reports that the average Airbnb in Overland Park earned $45,059 over 12 months at 49.2% occupancy. Averages hide seasonality, management cost and local rules. In Charleston, short-term rental permits and zoning are set by each municipality, so confirm the rules for the exact address before you build a plan around nightly rates.

Our perspective

We have managed thousands of properties across regional markets, including Charleston and Kansas City, and the pattern is consistent: investors do best when they choose the submarket for the strategy, not the other way around.

We see Charleston as a market that rewards patience and local knowledge. The right house in the right pocket, renovated properly and leased to a well-screened resident, holds value and demand. The wrong house, bought from a distance without an on-the-ground team, drains reserves.

That is why we run a pod-based team structure, keep maintenance in-house and select vendors transparently. Owners should not need to be in the city to know what their property is costing and earning. Our approach pairs local market expertise with investor-focused strategy so that returns are reliable and your hands-on involvement stays small.

If you are an Overland Park owner weighing Charleston, we would rather you run the numbers on both markets with us than guess. We are active in the Kansas City area too, so we can speak to both sides of the comparison.

MediaBeast

How Auben can help you invest in Charleston

We cover the full life of an investment property: brokerage to find and buy it, project management to renovate it, property management for leasing and day-to-day operations, and asset management to keep the portfolio aimed at your goals.

Aubenrealty

If you already own a property or have a target in mind, you can submit it to us and we will tell you how we would approach it. Our guide to rental property ROI is a good place to start building your own spreadsheet.

FAQ

Is Charleston a better place to invest than Overland Park?

It depends on your goal. Overland Park offers a documented supply shortage and steady renter demand, but high entry prices. Charleston offers a coastal, supply-constrained market with a larger tourism and in-migration story. Compare specific properties after taxes, insurance and vacancy, not city-wide medians.

Can I invest in Charleston from Kansas without moving?

Yes, many investors do. You need a local brokerage, inspector, lender and property manager, plus someone to oversee any renovation. Having the team in place before you make an offer is what keeps a remote purchase manageable.

How are rental properties taxed in South Carolina?

South Carolina generally taxes a non-owner-occupied home at a higher assessment ratio than a primary residence, which raises the annual bill. Confirm the current ratio and millage rate for the exact address with the county assessor and a tax professional before you underwrite.

What should a first-time investor look at first?

Start with net operating income: rent minus vacancy, taxes, insurance, management and maintenance. Then test the result against your financing. A deal that only works at the most optimistic rent is not a deal.

Should I sell an Overland Park property to buy in Charleston?

That is a tax and strategy question. A 1031 exchange may let you defer capital gains if you meet the rules, so talk to a qualified intermediary and your CPA before listing. Our 1031 exchange guide explains the basics.

Sources

Rental Showing Scheduling: A Practical Playbook for Landlords

The best way to schedule rental showings is to stop negotiating times one text at a time. Set fixed availability windows, ask a few screening questions before you book, confirm instantly, remind twice, and follow up the same day. A system like that fills your calendar with serious prospects and keeps your unit from sitting empty while you play phone tag.

This guide walks through each step, from the first inquiry to the post-tour application link. It also covers the questions owners ask most, including what to do when the unit is still occupied.

Aubenrealty
Spend Less Time Managing Rentals
Auben Realty provides property management and tenant placement services, helping landlords reduce hands-on involvement while managing the rental process.

TL;DR

  • Offer set tour windows instead of open-ended times. Weekend afternoons and early weekday evenings are the usual sweet spots.
  • Keep tours short, leave drive-time gaps, and stack several showings back to back at one property.
  • Send a confirmation right away, a reminder 24 hours ahead, and another 1 to 2 hours before the tour to cut no-shows.
  • When the unit is occupied, follow your lease and your state’s entry-notice rules. Many require about 24 hours’ written notice.
  • Send an application link right after the tour and follow up if it is not started.

Table of Contents

Scheduled tours or self-guided showings

Start with the format, because it decides everything else. A scheduled tour means a person meets the prospect at the property. A self-guided tour means the prospect gets access on their own, usually through a smart lock or lockbox code.

Scheduled tours give you a conversation. You answer questions, point out what matters and read the room. They cost you time, which is why the rest of this guide is about making that time efficient.

Self-guided tours save staff hours and let prospects visit at odd times. Industry reporting says AI-enabled self-guided tours can bring efficiency gains, though technology does not perfectly replicate a skilled leasing agent. For a vacant single-family home or a small multifamily building, many owners use a mix: self-guided for early-stage browsers, scheduled tours for finalists and for anyone with questions about the neighborhood, the lease or the renovation work.

A simple rule: if your average prospect needs reassurance, schedule a person. If your average prospect just needs to see the layout, self-guided is a reasonable fit. Whichever you choose, the scheduling principles below still apply, because even a self-guided visit needs a booked window, an identity check and a reminder.

Scheduled and self-guided rental tour comparison

Set availability, duration and buffers

The number one mistake is leaving your calendar open. Prospects then propose times that suit them, you counter, and half the conversations die before a tour is booked.

Instead, publish specific windows. Early afternoons on weekends, primarily Saturdays, and early evenings on weekdays while it is still daylight tend to work best. Pick one or two weekday evenings and one weekend block, and keep them consistent so you build a rhythm.

How long should a showing be?

Short. Scheduling guidance from a showing platform’s own documentation recommends showing durations of no more than 15 minutes unless there is a good reason, and suggests allowing drive-time gaps between listings. Fifteen minutes is enough for a typical apartment or small home. Larger homes, or a property with a yard, garage and outbuildings, may justify 20 to 30.

Cluster showings and add buffers

If you have one vacant property, offer several appointments in a row. A common approach is to group several showings at the same property and set buffer time between appointments. You travel once, you open the door once, and prospects who arrive while another group is leaving see that the unit is in demand.

A sample block for one Saturday:

Time What happens
1:45 p.m. You arrive, unlock, turn on lights, open blinds
2:00 p.m. Tour 1 (15 minutes)
2:20 p.m. Tour 2 (15 minutes)
2:40 p.m. Tour 3 (15 minutes)
3:00 p.m. Walk-through, lock up, log notes

Require advance notice

Same-day requests are tempting, but they produce the most no-shows and the most rushed prep. Some booking tools enforce this automatically. One platform’s documentation says automatic booking requires calendar integration and a 24-hour minimum notice, offering the earliest time that meets the rule when someone asks for a same-day or next-day tour. You can apply the same logic by hand: if you do not have a window in the next 24 hours, say so and offer the next one.

Screen before you book

Every wasted tour costs you an hour or more. A few questions before the appointment filter out people who cannot qualify. Ask:

  1. What is your target move-in date?
  2. How many people will live in the home?
  3. Do you have pets, and what kind?
  4. Are you comfortable with the monthly rent and the application requirements as listed?

Put your published criteria (income requirements, pet policy, lease length) in the listing so prospects self-select. Apply the same questions and the same criteria to everyone. Consistency protects you under fair-housing rules and makes your process easier to defend. For more on what a good screening process looks like after the tour, read how a property manager screens prospective tenants.

You can collect these answers through a booking form, so they arrive attached to the appointment. Pre-qualification questions and scheduling rules are the first two steps of a workable showing workflow, followed by automatic confirmations and reminders.

Confirm and remind: the no-show sequence

A tour that is booked but forgotten is the same as an empty slot. The fix is a short, predictable message sequence:

  1. Immediately after booking: a confirmation with the address, date, time, your name and a way to cancel or reschedule.
  2. 24 hours before: a reminder, with parking or entry instructions.
  3. 1 to 2 hours before: a short day-of reminder.

This three-step pattern is the one recommended for reducing no-shows. Make rescheduling effortless. A prospect who can tap a link to move their slot is far less likely to ghost you than one who has to text an apology.

Two small additions help. First, ask prospects to reply to confirm in the 24-hour message. A non-reply tells you to expect a gap and gives you time to fill it from a waitlist. Second, keep a short list of people who asked about times you could not offer, so a canceled slot becomes a booked one.

Scattered single-family homes: batch by area

If you manage houses spread across a metro area, scheduling gets harder. Showing scattered-site single-family rentals is a different job from showing units in one building, and batching showings by geographic zone prevents the zigzagging that eats an afternoon.

In practice, that means assigning each property to a zone, such as north side, south side or the beach communities, and offering tours by zone on set days. In a market like Dallas-Fort Worth or Houston, where traffic can turn a 10-mile trip into 45 minutes, this is the difference between five showings in an afternoon and two. Tell prospects honestly that a given day covers a given area, and offer them the next day for that zone if they miss it.

When the unit is still occupied

Occupied units add a second party to your schedule. Your first stop is the lease, and your second is your state’s landlord-tenant law. Rules vary a lot.

Permission matters even when notice alone would be enough. One housing-advice article quotes a lawyer who says a tenant given 24 hours’ notice must allow entry whether or not they agree, while another voice in the same piece says asking permission makes tenants more likely to tidy up. The second approach wins on results. A clean, well-lit unit shows better.

Practical habits for occupied showings:

  • Send written notice with the exact time window, and keep a copy.
  • Cluster showings into one or two blocks per week so the tenant is not disrupted daily.
  • Thank the tenant, and follow up when the visit is done.
  • Never stack so many entries that they start to look like harassment.

Good relationships with departing tenants also shape the condition of your unit at turnover. See three ways to make sure tenants take care of a rental home.

Safety, privacy and fair housing

Scheduling is also a risk-management step. A few protections cost nothing:

  • Verify who is coming. Collect a name and phone number at booking. For first-time visitors, let someone else know your schedule if you are showing alone.
  • Keep the process consistent. Offer the same windows, the same questions and the same follow-up to every prospect, and write down your criteria in advance.
  • Be careful with identity technology. Some self-guided systems ask visitors for face scans. Consumer advocates quoted by The Markup warn that scans may be improperly shared or used to exclude renters, and may falsely flag people of color. If you use access technology, collect only what you need, tell prospects what you collect and why, and ask your attorney about your state’s privacy rules.
  • Control access. Use time-limited codes for self-guided tours, and make sure the unit is secure after each visit.

For how technology and personal service fit together, see why human-centered service still matters in a tech-driven rental world.

After the tour: follow-up wins the lease

Most owners treat the tour as the finish line. It is the middle of the process. One leasing-automation firm argues that the post-tour handoff is where conversion is won or lost: send the application link right away and follow up if it is not started.

A simple follow-up plan:

  1. Within an hour: a thank-you message with the application link, the screening criteria and the deposit and move-in terms.
  2. Next morning: a short feedback question, such as whether anything about the home gave them pause.
  3. Two days later: a nudge if the application has not been started, and a clear note if another applicant is moving forward.

Automated feedback requests are a recommended final step, and the answers are useful. If three prospects in a row say the rent is high or the photos looked better than the carpet, you have market feedback you can act on before the vacancy drags on. To go further, read our landlord’s playbook for reducing vacancy and our tips for minimizing vacancy rates.

Choosing tools without overbuilding

You do not need a big system to start. A shared calendar, a booking link, a form with your screening questions and a set of message templates will carry you through a handful of showings a week. As volume grows, look for these features:

  • Calendar sync, so double-bookings cannot happen
  • Automatic confirmations and reminders
  • Buffer time and duration settings per property
  • Pre-qualification questions attached to each booking
  • Cancel and reschedule links
  • A record of every showing and its outcome

At portfolio scale, a unified system that handles scheduling, tracking and follow-up replaces spreadsheets and shifts you from reactive scrambling to proactive management. Pricing for these tools changes often, so check each provider’s current page before you commit. Our post on how great property managers embrace technology covers how to choose tech that helps rather than clutters.

Perspective: scheduling is a leasing system, not a calendar task

We manage rentals across ten regional markets, and the lesson repeats in every one: showings go wrong when they are treated as errands. They go right when they are treated as part of a leasing system that starts with the listing and ends with a signed lease.

That is why our pod-based team structure matters. A focused group of people knows your properties, your zones and your criteria. The person who answers an inquiry understands the home, the maintenance history and the neighborhood, and can book the right tour for the right prospect.

Our in-house maintenance team also helps at the showing stage. A unit that is cleaned, repaired and ready on the day of the tour shows better and leases faster. Technology handles confirmations and reminders, and our people handle the conversations that technology cannot.

For owners, the aim is simple: less time on the phone, fewer empty days, and a tenant who stays.

MediaBeast

Let us handle the showings

If you would rather not coordinate tours, reminders and follow-up yourself, our property management services include leasing and tenant placement, with local teams in each of our markets. You get the leasing coverage without giving up your weekends.

Aubenrealty

Looking for a home to rent instead? Browse our current rental listings and book a tour. If you are weighing a management company against a private landlord, this comparison of renting from property management companies and private landlords may help. Owners planning ahead for busy months can also use our leasing season tips.

FAQ

How many showings does it take to rent a home?

It varies by market, price and condition, so there is no reliable universal number. Some landlords report needing several showings per qualified applicant. Pre-screening questions, clear listing criteria and strong photos reduce the count, because they bring in people who can actually qualify.

What are the best times to show a rental?

Weekend early afternoons, primarily Saturdays, and early weekday evenings while it is still light tend to work best according to leasing guidance. Offer a consistent set of windows, and add a second weekday if demand is high. Always show in daylight when you can, so the unit looks its best and you stay safe.

Are tenants responsible for showings?

Generally, tenants must allow access with proper notice if the lease and state law say so, but they are not responsible for showing the home. In New York City practice, tenants are not expected to do the agent’s job. Check your lease and your state’s entry rules, and ask an attorney if you are unsure.

How much notice do I need to show an occupied unit?

It depends on your state. Many require 24 hours’ written notice, while others require more, such as two days in Alabama. Look up your state’s statute or ask a local landlord-tenant attorney before you schedule entries.

Should I use self-guided tours?

They can save time and widen your availability, especially for vacant units. Many owners pair them with scheduled tours for serious applicants. Whatever you choose, use time-limited access, collect only the identity information you need, and apply the same process to every prospect.

Sources

Charleston Rental Market in 2026: Rents, Occupancy and Outlook

Charleston, South Carolina is a high-rent, high-occupancy market that has cooled from its post-pandemic peak but not weakened. In Q3 2026, average rent was $1,805 with 93.0% occupancy and 3.0% annual rent growth, according to MMG Real Estate Advisors. If you live or invest in Houston and are looking at the Lowcountry, this guide covers what the numbers mean, what drives them, what to budget for and which rules apply.

Aubenrealty
Manage Charleston Rentals With Local Expertise
Auben Realty offers property management, renovation and tenant placement services for owners seeking local support in Charleston.

TL;DR

  • Charleston’s apartment market is stable: roughly 93% occupancy and low-single-digit rent growth in Q3 2026.
  • Figures differ by source and method. Averages run from about $1,800 to above $2,100 depending on what is counted.
  • New construction starts have dropped sharply, which supports rents. Coastal insurance is the big cost variable for owners.
  • Short-term rental rules in Charleston County are zone-based, capped by days and require annual permits, so long-term leasing is the simpler path.
  • Out-of-state owners, including Houston investors, do best with local management on the ground.

Table of Contents

Where Charleston rents stand right now

The most recent quarterly data comes from MMG Real Estate Advisors. Its Q3 2026 report puts average rent at $1,805, occupancy at 93.0% and annual rent change at 3.0%. Demand stayed strong, with absorption above pre-pandemic levels, though rent growth and occupancy eased slightly from the second quarter.

Q2 and Q3 Charleston rent and occupancy figures

The quarter before looked similar. In Q2 2026, average rent was $1,808 and occupancy 92.6%, with net absorption of 3,918 units over the trailing four quarters and annual rent growth of 1.3%. So the market has moved sideways on rent while occupancy ticked up. That is what a balanced market looks like.

Earlier in the year, multifamily vacancy was around 9.2% in Q1 2026, according to CBC Atlantic, with steady absorption supporting occupancy. The analysts describe a market moving into a more balanced phase after several years of rapid growth, where higher interest rates call for more conservative underwriting.

Why you will see different rent numbers

Readers often find two Charleston “average rents” that are hundreds of dollars apart and assume one is wrong. Usually both are right for what they measure.

Source What it reports Figure
MMG Real Estate Advisors Multifamily average rent, Q3 2026 $1,805
Select Commercial Average asking rent, August 2026 $2,137
RentCafe Average apartment rent, 2026 $2,175

MMG tracks the multifamily market broadly, including older, lower-priced stock. Asking-rent figures lean toward newer listings that are advertised right now. RentCafe also reports that studios average $2,145 and one-bedrooms $1,947, up 3.94% from $2,092 a year earlier. Use the lower numbers to judge what a stabilized building collects, and the higher ones to judge what a new lease costs today.

Select Commercial adds that Charleston is the most expensive apartment market in South Carolina by a wide margin, with August 2026 asking rents up 1.55% over the year. It credits the port, manufacturing, tourism and a historic peninsula with limited room to build.

What is driving demand and supply

Charleston rents did not get here by accident. The Post and Courier reported in November 2026 that rents have risen about 30% since before the pandemic, driven by population growth and limited housing supply, with new and longtime residents competing for the same space.

Three forces matter most for an owner.

  1. Employment anchors. The port, manufacturing and tourism give the market several sources of renter demand rather than one.
  2. Constrained land. Geography and preservation rules on the peninsula limit what can be built where demand is strongest.
  3. A slowing pipeline. MMG reports that apartment starts in Q2 2026 were down nearly 50% from a year earlier, and calls Charleston one of the stronger Southeast performers because new supply is slowing while renter demand holds.

That last point is the one to watch. Fewer starts today means fewer deliveries later, which tends to support occupancy and rents for existing properties. It also changes what owners do with the buildings they already have. Keeping units competitive with newer product is a matter of steady upgrades and quick, clean turns between residents, and apartment turnover services are one way multi-unit owners keep vacant days short.

One caution from the other direction: some analysts say investors should underwrite conservatively given the volume of new supply still entering the market. Units delivered in the last two years are still leasing up, and they set the competitive ceiling for older stock.

Renter leverage and concessions

Stable averages hide a more negotiable street-level reality. Rental Beast data for Q1 2026 indicated that nearly two in three active Charleston listings offered concessions, such as free rent or waived fees. Concessions are how landlords hold the headline rent steady while still filling units.

For an owner, this has practical consequences:

  • Price your listing against effective rent (rent minus concessions), not only the advertised number.
  • A well-presented, correctly priced home leases faster than one that waits for a rent bump.
  • Offering a modest incentive can protect a rent level that matters for refinancing or valuation.

How rents vary by property type and neighborhood

City-wide averages are a starting point, not a pricing tool. Within Charleston, the same dollar buys very different homes. Peninsula and nearby historic districts carry a premium because supply there cannot expand easily. Suburban and surrounding submarkets offer larger floor plans, yards and newer construction at lower rents per square foot.

The unit-size split in the figures above shows the shape: RentCafe’s studio and one-bedroom averages are both well above the MMG market-wide average, which tells you that newer, well-located buildings are pulling the top of the range. For a specific street or building, compare recent leases for the same bedroom count, age and amenities within a mile or two, rather than relying on any citywide figure.

Single-family rentals follow their own logic. Families who want space and a school zone often choose a house over an apartment and stay longer, which lowers turnover. You can see what is currently on offer through Charleston, SC homes for rent, and our article on turning houses for rent in Charleston into investment opportunities walks through how that segment pencils out.

What it costs to own a Charleston rental

Rent is only the top line. Charleston’s operating statement has a few lines that differ from what a Houston owner may be used to.

Insurance

Being near the coast changes insurance. Select Commercial notes that coastal insurance is often the single largest variable in a Charleston operating statement. Wind and hail coverage is priced for the coast, and flood coverage is typically a separate policy. Houston owners who have dealt with Gulf Coast storm exposure will recognize the pattern. Get actual quotes for the specific address before you set a purchase price, because a low insurance assumption can distort your returns and your financing.

Property taxes

South Carolina treats owner-occupied and investment property differently. Industry summaries state that owner-occupied homes are assessed at 4% while investment properties are assessed at 6%. Confirm the current assessment and millage for the parcel with the county assessor before you finalize a budget, since the rate you inherit as an investor is the higher one.

Maintenance and turnover

Humidity, salt air and summer storms are hard on roofs, exteriors and HVAC systems. Budget for preventive maintenance and keep a vendor bench you trust. Our approach is built on in-house maintenance and transparent vendor selection, so repair costs and scope are clear to owners rather than hidden in a markup. If you are weighing a renovation before leasing, our project management service oversees the scope, schedule and contractors for you.

Outdoor HVAC condenser beside a Charleston rental home

Management and leasing

Professional management costs money, but vacancy and tenant problems cost more. We can walk through fee structures for your specific property type, since fees depend on the property and service level. Our guide to finding tenants for rental homes in Charleston explains the leasing process in detail.

Rules that shape long-term and short-term rentals

Long-term rentals

Long-term leases in Charleston fall under South Carolina’s landlord-tenant law. It covers things like how security deposits are handled and returned, what must be disclosed in the lease and how notices work. Read the state’s residential landlord and tenant statute, or have a local property manager apply it for you, before you write or sign a lease. A lease that follows the state requirements from day one avoids most disputes later.

Short-term rentals

Short-term rentals are a different animal. Charleston County Ordinance #2387, adopted April 28, 2026, sets day caps and permit requirements by zoning district:

Category Annual day limit Zones listed in the ordinance
LHR 72 days per calendar year RM, AG-15, AG-10, AG-8, MHS, UR
EHR 144 days per calendar year AGR, RR, S-3, R-4, MHS
CGH No day limit RO, GO, NC, RC, CC

All categories require an annual zoning permit renewal and a business license. Note that this is a county ordinance, and the City of Charleston and neighboring towns have their own rules, so check which jurisdiction your property sits in. For most owners who want predictable income, a long-term lease avoids the day caps and the renewal cycle entirely.

Should a Houston owner or investor look at Charleston?

The two cities behave differently, and that is the case for owning in both. Charleston is a smaller, supply-constrained coastal market with premium rents and persistent demand. Houston is a large, sprawling market with a different cost structure. Holding assets in more than one metro spreads local risk, and Charleston’s tight land supply and slowing construction pipeline give it a different cycle from a big-metro market.

What works across both:

  • Underwrite conservatively. Use effective rents, real insurance quotes and a vacancy cushion.
  • Match the strategy to the asset. Single-family, multifamily and build-to-rent each have their own tenant profile and expense pattern.
  • Hire for presence. Remote ownership works when someone local handles showings, inspections, maintenance and resident relations.
  • Know your exit. If a sale is on your horizon, our brokerage services cover acquisition and disposition.

Our perspective

We manage rental homes and multifamily assets across 10 regional markets, Charleston and Houston among them, and the lesson that repeats is that averages do not pay your mortgage. Effective rent, days vacant and the true cost of operating a coastal property do.

Charleston rewards owners who treat leasing as a process. The market is stable, but concessions are common, and a home that is priced, photographed and shown well fills faster than one that is simply listed. That is why we organize our teams in pods: a focused group handles your property day to day, so the people who know your tenants and your vendors are the same people you talk to.

We also believe in keeping maintenance close. Our in-house maintenance team and transparent vendor selection keep costs visible and turns quick, and proactive resident retention reduces the vacancy that quietly erodes returns. For investors, we pair local market knowledge with investor-focused strategy, so the property is managed for long-term value and not only this month’s rent.

If you own in Houston and are looking east, you do not have to give up control to gain a second market. You need a partner on the ground who reports clearly and acts quickly.

MediaBeast

Work with Auben in Charleston

We have more than 15 years of experience and have served 2,700 properties. If you own or plan to buy a rental in Charleston, our property management team handles leasing, tenant placement, maintenance and day-to-day operations so you can stay hands-off. Investors building a portfolio can talk to us about asset management and multifamily and build-to-rent services.

Aubenrealty

Tell us about your property or your investment goals through our website, and we will start with the market, the numbers and a plan that fits.

FAQ

What is the average rent in Charleston, SC?

It depends on the source. MMG Real Estate Advisors reported $1,805 for the multifamily market in Q3 2026, while asking-rent trackers such as RentCafe report $2,175 for 2026. The gap reflects what each one counts. Use the lower figure for overall market performance and the higher one for newly advertised units.

Is the Charleston rental market strong for landlords?

Yes, with realistic expectations. Occupancy was 93.0% in Q3 2026 and rent growth was 3.0%, and new construction starts have fallen sharply. Concessions are common, so price to effective rent and keep homes well maintained to lease quickly.

Can I run a short-term rental in Charleston?

Only within the limits of the zoning district and jurisdiction. Charleston County’s Ordinance #2387 sets day caps of 72 or 144 days in some zones, none in others, and requires an annual zoning permit and business license. Check whether your address is in the county, the city or another town before you plan on it.

Can a Houston investor manage a Charleston rental remotely?

Yes, if a local manager handles leasing, inspections, maintenance and resident communication. Charleston-specific issues like coastal insurance, humidity-related upkeep and local rules are easier to manage with someone who works in the market every day. We serve both Houston and Charleston, so owners with properties in each can work with one team.

Sources

Why Real Estate Investors Need A More Integrated Approach

In a changing real estate market, the conversation is shifting from managing individual properties to managing the performance of an investment. 

For individual real estate investors, success has never been measured solely by whether a property is occupied or rent is collected. Cash flow, asset appreciation, operating expenses, tax considerations, and long-term portfolio objectives all play a role in determining an investment’s performance. 

Yet traditional property management has often focused primarily on day-to-day operations. 

As market conditions evolve, so do the expectations placed on real estate professionals. Today’s investors need more than someone to manage their properties. They need experienced partners who understand their objectives and can help them make informed decisions throughout the ownership life cycle. 

A Significant Market, A Changing Set of Needs 

According to John Burns Research & Consulting, the United States has approximately 14 million single-family rental homes, with 92.8% owned by smaller investors holding fewer than 350 properties. 

This fragmented ownership landscape represents an important segment of the real estate market—and one with increasingly complex needs. 

Higher operating costs, financing considerations, insurance premiums, and changing rental market dynamics require investors to think more strategically about the assets they own. 

The question is no longer simply, How is my property performing? 

It’s also, Is this property still the right investment for my goals? 

For some owners, the answer may involve improving operating efficiency or renovating an existing property. For others, it could mean evaluating a disposition, reinvesting in a different market, or transitioning from an aging asset into newer single-family rental or build-for-rent properties. 

From Property Operations to Investment Strategy 

At Auben, our approach has evolved around a fundamental principle: Every investor has different objectives, and real estate services should reflect those individual needs. 

Our four integrated service lines—property management, maintenance, project management, and brokerage sales—allow us to support owners across multiple stages of the investment life cycle. 

Property management provides the operational foundation. Maintenance and project management help preserve and improve asset performance. Brokerage services create opportunities to evaluate acquisitions, dispositions, and portfolio transitions. 

Together, these capabilities allow for a more comprehensive conversation about an investor’s real estate holdings. 

Rather than viewing each property or transaction independently, we see opportunities to connect operating performance with broader investment decisions. 

Technology Supports the Work. Relationships Drive the Value. 

Technology and artificial intelligence are transforming how real estate businesses operate, improving access to information, streamlining workflows, and creating opportunities for greater efficiency. 

But technology alone cannot replace the value of local expertise, personal relationships, and an understanding of an investor’s individual circumstances. 

The most effective model brings these capabilities together: sophisticated operating systems that give real estate professionals more time and better information to advise the people they serve. 

For individual investors, that means having a trusted point of contact who understands not only their properties, but also what they’re working toward. 

An Approach Built for Changing Markets 

Real estate markets rarely move in a straight line. 

In appreciating markets, investors may explore acquisitions, dispositions, or reinvestment opportunities. In more challenging conditions, attention may shift toward cash flow, expense management, retention, and asset repositioning. During periods of relative stability, improving an existing property’s performance may present the greatest opportunity. 

An integrated approach allows investors to evaluate these options in the context of their larger objectives rather than responding to each market change in isolation. 

Looking Beyond the Property 

As the single-family rental market continues to evolve, we believe the distinction between property management and real estate advisory services will become increasingly important. 

At Auben, our work extends beyond managing properties to helping investors pursue their individual real estate objectives. 

Our long-term vision is to be a trusted partner in building, optimizing, and managing real estate wealth—combining institutional capabilities with the personalized guidance and local knowledge individual investors deserve. 

Because ultimately, the most important investment conversation isn’t just about the property. 

It’s about what the property can help its owner achieve.

Sources 

Where to Invest in Jacksonville: A Guide for DFW Investors

Jacksonville is worth a serious look if you already invest in Dallas-Fort Worth and want a second market. It is growing, it has a diverse employer base, and its rents sit at a level that can work for single-family and multifamily buyers. The best places to start are the established in-town neighborhoods, the suburban rings in Duval, Clay and St. Johns counties, and the beach communities, each with a different tenant and a different risk profile. This guide covers the data, the areas, the property types and the Florida-specific costs you need to price before you buy.

Aubenrealty
Manage Your Jacksonville Investment
Auben Realty provides property management, renovation, and tenant placement for owners and investors across its regional markets.

Visit Auben Realty

TL;DR

  • Jacksonville’s population grew nearly 10% from 2020 to 2024, with job gains in manufacturing, healthcare, and transportation and warehousing.
  • Multifamily rents averaged $1,470 a month in Q2 2026, with occupancy near 90.9%.
  • Match the area to your goal: in-town neighborhoods for appreciation and renovation plays, suburbs for family rentals, beaches for premium rents and higher exposure to weather.
  • Underwrite insurance and wind mitigation before you make an offer. Florida carries costs a Texas investor does not expect.
  • Remote ownership works when you have local management, local maintenance and a local acquisition partner.

Table of Contents

Why DFW investors look at Jacksonville

DFW investors know what a fast-growing metro looks like: new employers, new rooftops, and competition for every decent deal. Many of them also know that the best DFW deals have become harder to underwrite as prices and competition rose. Jacksonville offers a similar growth story in a different regional economy, which is exactly what diversification is meant to do.

There is a second reason. A single-market portfolio carries single-market risks: one state’s tax regime, one set of property tax appraisal cycles, one local economy. Adding a Florida market spreads those risks. It also adds new ones, which we cover below, so the decision is a trade rather than a free win.

We operate in both places. Auben manages and invests across 10 regional markets, including Fort Worth and Dallas-Fort Worth in Texas and Jacksonville and Jacksonville Beach in Florida. We wrote about how Jacksonville cap rates look from a Fort Worth desk, and that comparison is the lens for this guide.

What the data says about Jacksonville demand

Start with the demand drivers, because rent growth and occupancy follow people and paychecks.

Indicator Figure Source
City population, July 1, 2025 1,017,689 U.S. Census Bureau
Median household income, 2020-2024 $69,872 U.S. Census Bureau
Metro unemployment rate, August 2026 4.3% U.S. Bureau of Labor Statistics
Total nonfarm employment, August 2026 803.8 thousand U.S. Bureau of Labor Statistics
Multifamily average rent, Q2 2026 $1,470 per month Cushman & Wakefield MarketBeat
Multifamily occupancy, Q2 2026 About 90.9% Cushman & Wakefield MarketBeat

Two readings matter. First, the growth is real, but the labor market has cooled: the Atlanta Fed reports that employers described flat hiring in 2025 as conditions moderated. Second, occupancy near 91% in multifamily, alongside a slowdown in new development compared with recent years, tells you the supply wave is easing. For a buyer that is a better entry point than a market in the middle of a construction peak, though it also means you should not underwrite aggressive rent jumps.

Public and private capital is also pushing into the urban core. The Jacksonville Business Journal points to projects such as the Stadium of the Future, a Four Seasons hotel and residences, and the Pearl Square and Gateway Jax developments as part of a cycle where large commitments build confidence and draw more private investment. For investors, that supports the case for neighborhoods within reach of downtown. It does not guarantee any single address will benefit, so treat it as a tailwind and underwrite the property on its own numbers.

Where to invest in Jacksonville: areas to evaluate

Jacksonville is geographically huge, and neighborhood quality changes block by block. Think in four buckets rather than a single citywide average. We describe the character of each below; pull current price, rent and days-on-market data for any specific ZIP code before you commit.

In-town neighborhoods near downtown

Riverside, Avondale, San Marco and the neighborhoods around them offer older housing stock, walkable commercial streets and proximity to the downtown projects described above. This is where renovation strategies tend to fit: older homes that benefit from a managed scope of work, then a lease to a renter who values location. Expect higher per-square-foot prices, historic character and more maintenance surprises in older construction. A renovation budget with a real contingency is not optional here.

Southside and Mandarin

The Southside corridor and Mandarin are suburban, convenient to employers, hospitals and shopping, and home to a large share of the area’s apartment communities and newer single-family neighborhoods. These areas typically attract renters who need a commute and a school zone, which supports steady demand for three- and four-bedroom homes. For DFW investors used to Plano or Frisco-style suburban renters, this will feel familiar.

Westside, Northside and Clay County

The Westside, the Northside and communities toward Orange Park in Clay County are where entry prices are generally lower and newer subdivisions and build-to-rent communities are more common. The Atlanta Fed notes job growth in transportation and warehousing, and the logistics employers behind that growth tend to draw workers to these parts of the metro. Lower entry price can mean thinner margins for error on vacancy and repairs, so underwriting discipline matters more.

Jacksonville Beach and the coast

The beaches carry premium rents and strong lifestyle demand. Our own market write-up on Jacksonville Beach rentals puts the average at $1,614 and covers what moves that number. Coastal addresses also bring higher insurance exposure, flood-zone questions and wind-mitigation costs. A beach property can be a strong asset when the insurance quote is in your spreadsheet from day one.

For a closer look at how we see the metro, our Jacksonville market page and the end-of-2025 market overview are good next reads.

Jacksonville Beach and the coast

Property types and strategies that fit different goals

The right place depends on what you want the property to do.

  • Cash flow with low involvement: newer single-family homes in suburban Duval and Clay county neighborhoods, managed professionally, aimed at long-term family tenants.
  • Appreciation plus value-add: older in-town homes bought below their potential and renovated under a controlled scope. This strategy rewards owners who do not manage the contractors themselves.
  • Scale: small multifamily or build-to-rent communities, where operating efficiency and a single management team lower per-unit costs.
  • Premium rents with higher risk: beach and coastal homes, where the insurance and mitigation line items decide whether the numbers hold.

If you are a first-time out-of-state investor, begin with one single-family home in a suburban area, learn how the market and the management work, then scale. If you are an experienced DFW owner with several doors, build-to-rent or multifamily can give you a more efficient structure. Our multifamily and build-to-rent services are designed for that second group.

Why local housing needs matter for this choice is something we cover in our piece on local housing needs and better investments. The short version: buy what the neighborhood’s renters actually need, not what looks good on a spreadsheet.

Costs and risks Texas investors should price in

This is the section that separates a good Jacksonville purchase from a regretted one. A Texas portfolio has its own burdens, mainly property taxes. Florida replaces some of them with others.

Insurance and wind mitigation

Hurricane exposure shapes insurance cost. Florida’s Office of Insurance Regulation explains that insurers must provide information on available hurricane-mitigation discounts, and that an authorized inspector completes the Uniform Mitigation Verification Inspection Form (OIR-B1-1802), effective April 1, 2026. In practice, ask for that inspection on any home you are evaluating, and ask your insurance agent how roof age, roof shape, shutters and opening protection change the quote. Roof condition is the biggest variable in many cases, so it helps to understand how to fortify a Florida roof before you budget for repairs and upgrades.

Florida rental roof and fitted storm shutters

Flood zone and elevation

Check the flood zone designation and the property’s elevation for every address, including ones that look inland. Flood insurance is priced separately from homeowners coverage, and lenders may require it depending on the zone. Get a quote before you go under contract.

Taxes, reserves and vacancy

Florida investment properties are assessed differently from homesteaded homes, and the assessed value can change after a sale. Confirm the current rules with the Duval County Property Appraiser (or the appraiser in the county you are buying in) and model the tax bill at your purchase price, not the seller’s. Keep a reserve for vacancy and capital items. Occupancy near 91% in multifamily is healthy but not a guarantee for any one unit.

Remote ownership risk

The quiet risk for a Texas-based owner is distance. A leak found three weeks late, a contractor you cannot verify, a lease you cannot enforce: these cost more than any rate difference. Plan for local eyes on the property.

How to compare a property’s income and expenses

Use the same discipline you use in DFW, with Florida line items added.

  1. Pull rent comparables for the exact neighborhood and bedroom count, not the metro average. The $1,470 multifamily average and the $1,614 Jacksonville Beach figure show how widely rents differ by area.
  2. Build the expense side honestly: property taxes at your purchase price, a real insurance quote with wind mitigation and flood, management fees, maintenance reserves and vacancy.
  3. Calculate net operating income and the cap rate, then compare with the numbers in our Jacksonville cap rate analysis.
  4. Inspect the big systems: roof, HVAC, plumbing and drainage. Order the wind mitigation inspection before closing.
  5. Check the neighborhood’s demand: nearby employers, commute times, school zones and how long comparable rentals sit before leasing.
  6. Price the management and renovation plan before you close, so the first-year budget contains real figures.

Run the model three ways: base case, a case with rents 5% lower, and a case with insurance higher than quoted. If the deal only works in the best case, move on.

Our perspective on investing in Jacksonville

Out-of-state investors rarely lose money because they picked the wrong city. They lose it because they bought without local data, hired management that could not respond quickly, or skipped the insurance math.

At Auben, our approach combines local market expertise with investor-focused strategies. Our pod-based team structure gives each owner a focused group that knows the neighborhood, our in-house maintenance keeps repairs fast, and our vendor selection process is transparent. Proactive resident retention and technology-enabled reporting support steadier occupancy and clearer numbers for owners who live hundreds of miles away.

We have served 2,700 properties across 10 regional markets over more than 15 years, including both Fort Worth and Jacksonville. That is why we encourage DFW investors to treat Jacksonville as a managed, underwritten decision: pick the area for your goal, price the Florida risks first, and put local operators in place before closing.

MediaBeast

Work with Auben in Jacksonville

If you want a Jacksonville purchase handled end to end, we can help with acquisition through our brokerage services, renovation oversight, leasing and tenant placement, and day-to-day Jacksonville property management. Owners with larger portfolios can add asset management to keep the strategy on track.

Aubenrealty

If you are comparing markets, start with a conversation about your goals and budget. Visit Auben Realty to reach the team, or browse homes for rent in Jacksonville to see the kind of properties we lease.

FAQ

Is Jacksonville a good place for a Dallas-Fort Worth investor to buy?

It can be, if your goal is diversification and you have local management. The city has grown nearly 10% from 2020 to 2024, and multifamily occupancy sits near 91%. Hiring has cooled, so underwrite steady rents rather than rapid growth.

What are the best areas in Jacksonville to invest in?

It depends on your strategy. In-town neighborhoods like Riverside, Avondale and San Marco suit value-add buyers, Southside and Mandarin suit family rentals, and the Westside, Northside and Clay County suit lower entry prices and newer builds. Beach communities offer premium rents with higher insurance exposure.

What extra costs should I expect compared with Texas?

Insurance is the main one, especially for homes near the coast or with older roofs. Florida’s insurance regulator describes a wind mitigation inspection form that can support discounts. Also check flood zones and model property taxes at your purchase price.

Can I own a Jacksonville rental from Texas?

Yes. Many investors do, using a local brokerage for acquisition, a property manager for leasing and maintenance, and clear monthly reporting. The key is having someone local who can inspect, respond and verify work.

How much does a Jacksonville rental cost to manage?

Management pricing depends on the property type and scope. Contact our team through the Jacksonville property management page for a quote based on your property.

Sources